Hastings Home Insurance Phone Number Explained

Written by Brijesh Patel
Reviewed by Prajesh Manvar
7 min read
Updated: 13 Nov 2026
Hastings Home Insurance Phone Number Explained

The Hastings home insurance phone number most customers need is the Hastings Direct customer service line, with new-business and existing-customer calls handled on separate 0333 numbers. Hastings Direct publishes these on its official website, and 03 numbers cost no more than a standard national-rate call and count towards any inclusive minutes on your phone plan.

Before you call about a quote, a renewal, a change or a claim, it helps to know what you are actually buying. Home insurance usually comes as combined buildings and contents cover, and the price depends on your sum insured, your excess and the policy exclusions. Free Price Compare is FCA-authorised and compares home insurance from a panel of 42 providers, so you can line up Hastings against the wider market before committing.

Quick Answer: Hastings Home Insurance Phone Number Explained

  • 03 numbers cost no more than a national-rate call and use inclusive minutes.
  • Hastings Direct publishes separate lines for new quotes and existing customers.
  • Lines typically run Mon–Fri, with shorter Saturday and Sunday hours.
  • Average UK combined buildings and contents cover was £383 a year (ABI, Apr–Jun 2026).
  • Buying buildings and contents separately averaged around £44 more a year.

Last updated: October 2026

Written by the Free Price Compare editorial team | Reviewed October 2026

How to contact Hastings Direct about home insurance

Hastings Direct handles home insurance enquiries through its customer service team, with separate telephone lines for new quotes and for existing policyholders, all published on the official Hastings Direct website. The numbers are 03 lines, which under Ofcom rules cost no more than a standard geographic call and are included in any inclusive-minutes allowance on your mobile or landline plan.

Always take the current number straight from the official Hastings Direct site or from your policy documents rather than from a third-party listing, because insurers update their contact routes and some numbers quoted online are outdated or region-specific. If you hold a policy, your renewal letter and schedule show the exact line to call for your account.

For non-urgent changes, Hastings Direct also offers self-service through its app and online account, plus a live chat option on its website. Keeping your policy number to hand speeds up any call, as the adviser can pull up your cover, excess and renewal date immediately.

Compare home insurance from 42 providers

Is there a Hastings home insurance 0800 freephone number?

Hastings Direct’s current home insurance customer service runs on 03-prefixed numbers rather than an 0800 freephone line. Calls to 0800 and 0808 numbers are free from mobiles and landlines, while 03 numbers cost no more than national-rate calls and count towards inclusive minutes, according to Hastings Direct’s published call-charge information.

You may remember an older freephone jingle from Hastings Direct advertising, but the number you see on advertising at a given time is not always the line used for an existing home policy. For accuracy, use the contact details on your policy documents or the official website, since the 03 customer service route is the one tied to home insurance accounts. If cost is a concern, an 03 call is still inexpensive and uses your bundled minutes.

What are the opening hours for Hastings home insurance?

Hastings Direct home insurance phone lines typically open Monday to Friday during the day, with reduced hours on Saturday and a short window on Sunday. Exact opening hours change, so confirm the current times on the official Hastings Direct website or your policy paperwork before calling, as insurers adjust hours around bank holidays and seasonal demand.

If you are trying to reach a human on a Sunday or outside standard hours, the app and online account let you make many changes without calling, and claims lines often operate on a different, longer schedule than general customer service. For a burst pipe, escape of water or other emergency, use the claims or home emergency number shown on your documents rather than waiting for general opening hours.

Know what you are paying for before you call

Compare combined buildings and contents cover across 42 UK providers in about five minutes.

How do I make a home insurance claim with Hastings Direct?

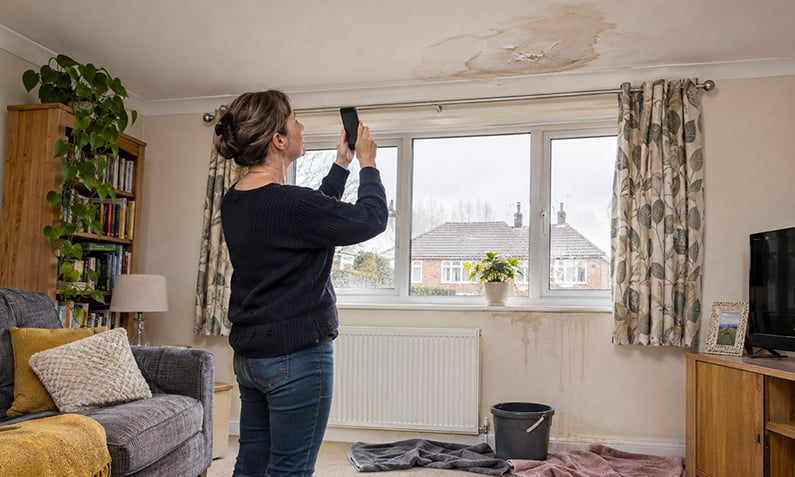
To make a home insurance claim with Hastings Direct, call the dedicated claims number shown on your policy schedule as soon as it is safe to do so, and have your policy number, the date and cause of the loss, and photos of any damage ready. Claims lines usually run longer hours than general customer service, and for emergencies such as an escape of water you should also contact any home emergency provider listed on your documents.

When you report a claim, you will be asked about the excess that applies, which is the amount you pay towards a claim before the insurer covers the rest. The quicker you report and document the damage, the smoother the process, and you should avoid starting non-urgent repairs until the insurer confirms what it will cover. Our step-by-step walkthrough on how to file a home insurance claim explains what evidence to gather and what to expect at each stage.

If a claim stalls or you are unhappy with how it is handled, you can raise a formal complaint with the insurer first. If it is not resolved within eight weeks, you can refer it to the Financial Ombudsman Service, which settles disputes between consumers and FCA-regulated firms free of charge.

How do I make a home insurance claim with Hastings Direct

How do I cancel my Hastings home insurance?

You cancel Hastings Direct home insurance by contacting the customer service team by phone, through the app or online account, and the outcome depends on when you cancel. Within the 14-day cooling-off period you can cancel and receive a refund for the unused portion, minus any cover already used and a possible administration fee, under FCA rules that require insurers to give a cancellation right on home policies.

After the cooling-off period, you can still cancel mid-term, but the refund is pro-rata for the remaining days and a cancellation charge may apply, as set out in your policy terms. If you pay monthly, cancelling may also end the credit agreement that funds your premium, so check the figures before you confirm. Keep a written record of your cancellation and the confirmation, and never cancel an existing policy until replacement cover is in force, to avoid any gap.

See how your renewal compares to the market

How much does home insurance cost in the UK right now?

Average UK combined buildings and contents cover cost £383 a year in April–June 2026, according to ABI Property Insurance Premium Tracker data (published 3 August 2026). That was £8 higher than the January–March 2026 average of £375 and £9 lower than a year earlier, marking the first quarterly rise since early 2025. Figures reflect prices customers actually paid, not quoted estimates.

Cover type Average price paid (Apr–Jun 2026) Change vs year earlier
Combined buildings & contents £383 a year £9 lower
Buildings only £309 a year £16 lower
Contents only £118 a year £11 lower

Figures are indicative and may change. Source: ABI Property Insurance Premium Tracker, Apr–Jun 2026.

Buying buildings and contents as separate policies at those averages totals £427 a year, around £44 more than the average combined policy, so combined cover is usually the cheaper route for owner-occupiers. At £383 a year, a combined policy works out at roughly £32 a month before any instalment interest; paying monthly on a representative 21% APR example lifts that to around £35 a month. A Hastings-specific premium depends on your property, postcode, sum insured and excess, so compare quotes rather than relying on an average. Our guide to home value and insurance cost explains how your rebuild figure drives the buildings price.

What should you ask before you buy or renew?

The three numbers that decide whether a home policy is good value are the sum insured, the excess and the exclusions, so check these before you commit to Hastings or anyone else. The sum insured for buildings should match the rebuild cost of your home, not its market value, and the contents sum insured should reflect what it would cost to replace everything you own.

  • Buildings sum insured: set to the full rebuild cost, including demolition and professional fees, so you are not underinsured.
  • Excess: check both the compulsory and any voluntary excess, as a higher voluntary excess lowers the premium but raises what you pay at claim time.
  • Exclusions and conditions: wear and tear, gradual damage and unoccupancy are commonly excluded, and some claims require you to meet security conditions.
  • Add-ons: accidental damage, home emergency cover and legal expenses are often optional, so confirm what is included.

Reading the exclusions is where most disappointment is avoided, because standard home insurance does not cover ongoing deterioration or poor maintenance. Our guide to home insurance exclusions sets out the gaps to watch for, and the best home insurance guide explains how to weigh cover quality against price rather than picking on headline cost alone.

Compare combined buildings and contents cover

Should you shop around instead of auto-renewing?

Shopping around at renewal is usually worth it, because loyalty rarely gets rewarded and the cheapest provider changes from year to year. The FCA banned the practice of charging existing customers more than new ones for the same cover in 2022, but that does not guarantee your renewal is the best price available across the market.

Citizens Advice has previously raised concerns about long-standing customers overpaying, a theme covered in our report on home insurers overcharging loyal customers. Comparing quotes takes about five minutes with us, and lining up Hastings against the rest of a 42-provider panel is the clearest way to check your renewal is competitive. If you need a quick reference for another insurer’s lines, our AA home insurance contact number guide follows the same format.

Should you shop around instead of auto-renewing

FAQs about hastings home insurance phone number

What is the Hastings Direct customer service phone number?

Hastings Direct publishes separate 03 customer service numbers for home insurance on its official website, with one line for new quotes and another for existing customers. These 03 numbers cost no more than a standard national-rate call and count towards any inclusive minutes on your phone plan. Always confirm the current number on the official Hastings Direct site or your policy documents, as contact routes change.

What is the Hastings Direct email address?

Hastings Direct handles most home insurance enquiries by phone, app, online account and live chat rather than general email. For a current contact email or complaints address, check the contact page on the official Hastings Direct website or your policy documents. Using the app or online account is usually the fastest way to make changes without calling.

How do I cancel Hastings car insurance?

Car insurance is handled separately from home insurance within a Hastings Direct account, so cancel it on the motor customer service line or through the app. The same cooling-off and pro-rata refund rules apply, and a cancellation charge may be deducted. Never cancel until your replacement motor cover is in force, as driving uninsured is a legal offence.

How do I contact Hastings Direct via live chat?

Hastings Direct offers live chat through its official website and app, which is useful for quick questions and simple policy changes outside of busy phone times. Have your policy number ready so the adviser can find your cover. Live chat is not usually the route for reporting an urgent claim, where you should call the claims line instead.

Does house insurance cover ongoing repair work?

Standard home insurance covers sudden, accidental events such as storm, fire, flood or escape of water, not ongoing repairs caused by wear and tear, gradual deterioration or poor maintenance. If a one-off insured event causes damage, the resulting repair is usually covered subject to your excess and conditions. Pre-existing or slowly developing problems are typically excluded.

Are home insurance payouts taxable?

Home insurance payouts that compensate you for damage, loss or replacement of your property are not usually treated as taxable income, because they restore you to the position you were in before the loss rather than being a profit. Different rules can apply to business use or rental property, so take professional advice if your situation is more complex. Keep all claim documents for your records.

How often should I shop around for home insurance?

Compare home insurance every year at renewal rather than letting a policy auto-renew, because the cheapest provider changes and loyalty rarely earns a better price. Comparing takes about five minutes and lets you check your renewal against the wider market. Review your cover levels too, as home improvements or new valuables may change the sum insured you need.

Is combined buildings and contents cheaper than separate policies?

Combined buildings and contents cover is usually cheaper than buying the two separately. At April–June 2026 averages, separate policies totalled around £427 a year against £383 for a combined policy, roughly £44 more. Combined cover also means one insurer, one excess arrangement for many claims and one renewal date to manage.

What happens if my home insurance claim is delayed or mishandled?

If a home insurance claim is delayed or handled poorly, raise a formal complaint with the insurer first and keep a written record of all contact. If it is not resolved within eight weeks, or you receive a final response you disagree with, you can refer it free of charge to the Financial Ombudsman Service. For major, long-running losses, keeping dated photos and correspondence strengthens your case.

Also Read Related Articles


Information correct as of 20 October 2026. Prices, tariffs, policy details and providers change frequently, so please check the latest details before making a decision. This article is for general information only and does not constitute financial advice. Free Price Compare is authorised and regulated by the Financial Conduct Authority (FCA).

4000+ reviews