Car Insurance Write-Off Categories Explained

Written by Prajesh Manvar
Reviewed by Tim Bailey
6 min read
Updated: 23 Oct 2026
Car Insurance Write-Off Categories Explained

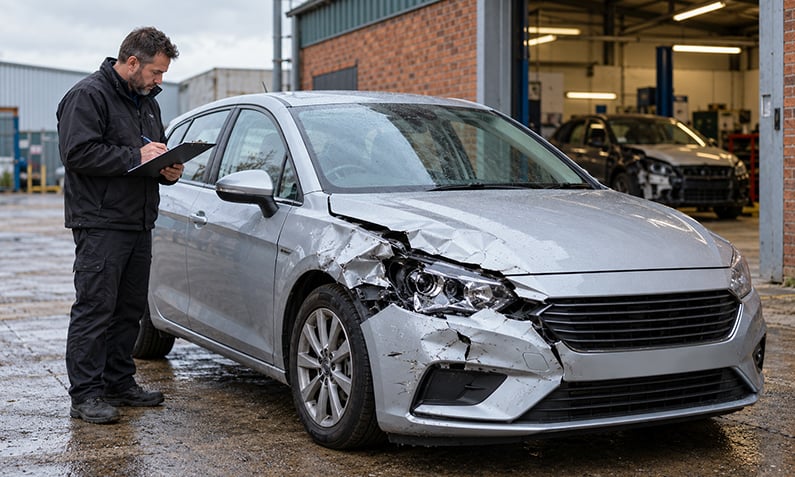
Car insurance write-off categories are the four codes UK insurers use to grade a damaged vehicle: Category A, Category B, Category S and Category N. The code records how badly a car is damaged and whether it can ever legally return to the road. Category A and B vehicles must be destroyed; Category S and N vehicles can be repaired and driven again if the work is done properly and they are roadworthy.

A vehicle is normally written off when the insurer decides repairing it costs more than it is worth, or the damage makes it unsafe to fix. At that point the insurer usually pays you the car’s current market value rather than funding the repair. The category then stays attached to the vehicle’s history for life, which matters if you later buy or sell it.

For most Free Price Compare buyers, who are typically in their late 40s or 50s and choosing comprehensive cover, the practical questions are simple: what does my category mean, can the car go back on the road, and will it affect my cover and premium. Those are answered below using the current GOV.UK and Association of British Insurers (ABI) definitions.

Quick Answer: Car Insurance Write-Off Categories Explained

  • Cat A and Cat B cars must be crushed and cannot legally return to the road.
  • Cat S has repairable structural damage; Cat N has repairable non-structural damage.
  • A write-off usually means the insurer pays the car’s market value, not repair cost.
  • The DVLA will not re-register a Category A or B vehicle.
  • Always tell your insurer a car’s write-off history; underwriting rules vary by insurer.

Last updated: October 2026

Written by the Free Price Compare editorial team | Reviewed October 2026

What do Cat A, B, S and N actually mean?

Cat A, B, S and N are the four UK insurance write-off categories that describe how badly a car is damaged and whether it can go back on the road. The system replaced the older C and D categories, which were retired in 2017. According to GOV.UK, in guidance updated on 2 October 2026, Category A means scrap only, Category B means break for salvageable parts, Category S means repairable structural damage, and Category N means repairable non-structural damage.

Category A and B are treated as an “actual loss”: the vehicle cannot or should not come back as a complete car. Category S and N are a “constructive loss”, meaning repair is physically possible but the insurer judged it uneconomical compared with the car’s value. The ABI applies these codes through its voluntary Salvage Code of Practice, which all ABI member motor insurers follow; the ABI updated that code in May 2025.

Category Damage Can it return to the road?
Cat A Beyond repair; whole vehicle must be crushed No
Cat B Body shell must be crushed; parts may be reused No (parts only)
Cat S Repairable structural damage (e.g. chassis or crumple zone) Yes, if properly repaired and roadworthy
Cat N Repairable non-structural damage (e.g. electrics, panels, lights) Yes, if properly repaired and roadworthy

Source: GOV.UK insurance write-off guidance, updated 2 October 2026. Figures are indicative and may change.

Compare comprehensive car insurance quotes

Why would an insurer write off a car that looks fixable?

An insurer writes off a car when the cost of repairing it reaches a point where replacing it makes more financial sense, even if the repair bill looks lower than the payout. This is why a car with what seems like modest damage can still be declared a total loss. The decision is driven by the car’s current market value, the full repair estimate including parts, labour and a courtesy car, and whether the damage affects safety.

Some insurers use a repair-cost threshold of roughly 50% to 70% of a car’s market value as a trigger for writing it off, though this is an insurer-specific underwriting guide rather than an industry-wide rule. On an older or lower-value car, repairs reach that threshold quickly. That matters for Free Price Compare users: around 43-48% of our car insurance quotes are for a car valued between £1,000 and £5,000 (Free Price Compare data, Jan-Jun 2026), and lower-value cars are written off more readily because repair costs are a larger share of their worth.

When your car is written off, the insurer normally pays its market value at the time of the incident, minus any excess you owe. If you disagree with the valuation, you can challenge it with evidence of comparable cars for sale, and escalate to the FCA-regulated Financial Ombudsman Service if the dispute is not resolved.

How does the excess affect a write-off payout?

A car insurance excess is the fixed amount you agree to pay towards any claim before the insurer pays the rest, and it is deducted from your write-off payout. If your car is valued at £4,000 and your total excess is £500, you receive £3,500. Your excess is made up of a compulsory excess set by the insurer plus any voluntary excess you chose when buying the policy.

Choosing a higher voluntary excess lowers your premium but increases what you lose if the car is written off, so it is worth balancing the two. Our guide to how voluntary and compulsory excess work explains how to set a level that suits your car’s value. If the accident was not your fault, you may be able to recover the excess from the other driver’s insurer, as covered in our guide on paying excess when you are not at fault.

Why would an insurer write off a car that looks fixable

Worried about your excess?

Check how voluntary and compulsory excess affect your payout before you buy.

Can a written-off car legally go back on the road?

A written-off car can legally return to the road only if it is a Category S or Category N vehicle that has been properly repaired and is roadworthy. Category A and Category B vehicles cannot, because GOV.UK requires Cat A cars to be crushed entirely and Cat B body shells to be destroyed. The DVLA will not re-register a Category A or B vehicle, so neither can ever carry a valid registration again.

For a repaired Cat S or Cat N car, there is no government-mandated re-inspection scheme in place for standard private cars, but the repairs must be done to a safe, roadworthy standard and the car needs a valid MOT if it is three years old or more. If you kept your own car after it was declared a total loss, you buy the salvage back from the insurer and are responsible for ensuring it is roadworthy before driving it.

What happens if I repair the car myself without a claim?

A car only receives a write-off category when an insurer records it as a total loss following a claim. If you have an accident and pay for the repairs yourself without involving your insurer, the car is not assigned a Cat S or Cat N marker, because no insurer has declared it a total loss. The category is created by the insurance process, not by the damage itself.

This is a common point of confusion. A privately repaired car carries no write-off marker, but any insurer-recorded total loss stays on the vehicle’s history permanently and will show on an HPI or history check.

See what affects your car insurance quote

Should I buy a Cat S or Cat N car?

Buying a Cat S or Cat N car can save you money against the same model with a clean history, but it carries risks that are worth weighing carefully. A Category N car had non-structural damage, such as cosmetic panels, lights, electrics or interior trim, while a Category S car had structural damage to parts like the chassis or crumple zones that was repaired. Cat N damage is generally lower risk than Cat S, but “non-structural” does not guarantee the damage was minor.

Before buying a repaired write-off, get an independent inspection and a vehicle history check, ask for proof of who carried out the repairs, and confirm it has a valid MOT. Two practical points often catch buyers out: a written-off car typically sells for less than an equivalent clean car, and that lower resale value will apply again when you come to sell it.

  • Commission an independent mechanical and bodywork inspection before committing.
  • Run a history check to confirm the exact category and any outstanding finance.
  • Ask for repair invoices and photographs of the damage and the work done.
  • Confirm you can get cover and agree a valuation with an insurer before you buy.

Will a Cat S or Cat N car be harder to insure?

Insuring a repaired Cat S or Cat N car is possible with many providers, but availability, cover level and price are set by each insurer’s own underwriting, so there is no universal rule. Some insurers accept repaired write-offs readily; others decline them or ask for proof of roadworthy repairs. You must disclose the write-off history when you apply, even if the insurer does not ask directly, because failing to do so can invalidate your cover.

Because acceptance varies, comparing across a broad panel helps. Free Price Compare compares car insurance from a panel of 130+ insurers, which widens the chance of finding one that covers a repaired write-off at a workable price. Around 88-89% of our car insurance quotes are for comprehensive cover (Free Price Compare data, Jan-Jun 2026), and comprehensive is usually the sensible choice on a repaired car where you still want protection for damage to your own vehicle.

Compare quotes from 130+ UK insurers

What a write-off means if your car is on finance

If a financed car is written off, the insurer’s payout goes towards settling the outstanding finance first, and you keep anything left over. A problem arises when the market-value payout is less than the balance you still owe, leaving you in negative equity and liable for the shortfall. This is most common on PCP and hire purchase agreements in the early years, when depreciation outpaces how much of the loan you have repaid.

Guaranteed Asset Protection (GAP) insurance is designed to cover that gap between the insurer’s payout and the finance balance. If you drive a financed car, our guide on what happens when a car on finance is written off walks through the settlement order and your options. You should also tell the finance company promptly, as the car remains their asset until the agreement is cleared.

Does a write-off affect my no-claims bonus?

A no-claims bonus is the discount insurers give for each consecutive year you do not make a claim, and a write-off claim normally counts against it unless the accident was not your fault and your insurer recovers its costs in full. If you have protected no-claims bonus, an agreed number of claims will not reduce your discount, though it can still affect your overall premium at renewal.

A fault write-off typically resets or reduces your no-claims bonus, which raises future premiums. Around 16-19% of Free Price Compare car insurance quotes come from drivers with 20 or more years of no-claims bonus (Free Price Compare data, Jan-Jun 2026), and protecting that record is worth checking before you accept a settlement that logs the claim as fault.

What a write-off means if your car is on finance

FAQs about car insurance write-off categories

What is the difference between Cat S and Cat N?

A Category S car had structural damage, meaning parts of the frame such as the chassis or crumple zones were affected and then repaired. A Category N car had non-structural damage, such as cosmetic panels, electrics, lights or trim. Both can legally return to the road once properly repaired and roadworthy, but Cat S damage is generally considered more serious.

Can I keep my car if it is written off?

Yes, with a Category S or Category N write-off you can usually ask the insurer to let you keep the car. The insurer pays you the market value and then deducts the salvage value so you retain the vehicle. You are then responsible for repairing it to a roadworthy standard before driving it, and you must insure it with its write-off history disclosed.

Why would an insurer write off a car when repairs cost less than the payout?

Insurers factor in more than the raw repair quote, including parts, labour, a courtesy car and the risk of hidden damage, then weigh that against the car’s value and safety. On lower-value cars, those combined costs quickly exceed a sensible proportion of what the car is worth. If repairing it is uneconomical or unsafe, the insurer declares it a total loss and pays the market value instead.

Does a write-off category stay with a car forever?

Yes, once an insurer records a car as a total loss, the category stays on the vehicle’s history permanently and shows on a vehicle history check. This applies to Category S and N cars that are repaired and sold on. It is why buyers run history checks and why repaired write-offs usually sell for less than equivalent cars with a clean record.

Do I have to tell my insurer my car was previously written off?

Yes, you must disclose a car’s write-off history when applying for insurance, even if the insurer does not ask the question directly. Failing to disclose it is a material non-disclosure that can invalidate your cover or lead to a refused claim. Because acceptance and pricing vary, it is worth comparing several insurers to find one that covers repaired write-offs.

How much excess will I pay if my car is written off?

Your total excess, which is the compulsory excess set by the insurer plus any voluntary excess you chose, is deducted from the write-off payout. So if your car is valued at £3,000 and your combined excess is £400, you receive £2,600. If the accident was not your fault, you may be able to recover the excess from the other driver’s insurer.

Can I challenge the write-off valuation my insurer offers?

Yes, you can dispute a write-off valuation if you think it is too low. Gather evidence of comparable cars for sale with similar age, mileage and specification, and present it to your insurer. If you cannot reach agreement, you can complain to the insurer formally and then escalate the dispute to the Financial Ombudsman Service, which reviews unfair settlements for free.

What happens to a car on finance if it is written off?

The insurer’s payout is used to settle the outstanding finance first, and you keep any surplus. If the payout is less than the balance owed, you are liable for the shortfall unless you have GAP insurance to cover the difference. You should notify the finance company as soon as the car is declared a total loss, as the vehicle remains their asset until the agreement is cleared.

Will my car still get a category if I repair it myself?

No, a car only receives a write-off category when an insurer records it as a total loss following a claim. If you pay for repairs yourself without involving your insurer, no category is assigned because no insurer has declared it a total loss. The marker is created by the insurance process, not by the damage itself.

Is a Cat N car safe to buy?

A Cat N car can be safe to buy if it has been properly repaired, but “non-structural” does not guarantee the damage was minor, so inspect it carefully. Get an independent mechanical and bodywork inspection, ask for repair invoices and photographs, confirm a valid MOT and run a history check. You should also confirm you can insure it at an acceptable price before you commit.

How many insurance claims can I make in a year?

There is no fixed legal limit on how many car insurance claims you can make in a year, but each claim can affect your premium and your no-claims bonus. Making several claims in a short period can lead some insurers to increase your price at renewal or decline to offer cover. A write-off claim is usually a single large claim that counts against your record unless it was no-fault and fully recovered.

Can a Category A or B car ever be re-registered?

No, a Category A or Category B car cannot be re-registered or legally driven on UK roads. A Category A car must be crushed entirely, and a Category B car’s body shell must be destroyed, although salvageable parts may be reused in other vehicles. The DVLA will not re-register either category, so neither can ever carry a valid registration again.

Also Read Related Articles


Information correct as of 16 October 2026. Prices, tariffs, policy details and providers change frequently, so please check the latest details before making a decision. This article is for general information only and does not constitute financial advice. Free Price Compare is authorised and regulated by the Financial Conduct Authority (FCA).

4000+ reviews