


What Happens To Your Premium After A Claim

Written by Tim Bailey
Reviewed by Pratik Aghera
7 min read
Updated: 6 Nov 2026
What Happens To Your Premium After A Claim

Your premium after a claim usually rises at renewal, even if the accident was not your fault, because insurers treat any claim on your record as a sign of higher future risk. How much it changes depends on who was at fault, whether your insurer recovers its costs, your policy terms and your wider risk profile. There is no single fixed percentage that applies across every insurer in the UK.

Two things move independently after a claim: your no-claims discount (the years of claim-free driving you have built up) and the underlying price your insurer charges. A claim can reduce one, the other, or both. The Financial Ombudsman Service confirms that protecting your no-claims discount keeps the discount years intact but does not stop the base premium going up.

Most Free Price Compare car insurance buyers hold comprehensive cover and are in their late forties to fifties, so this explainer focuses on what a claim realistically does to your renewal and how to keep the price as low as possible.

Quick Answer: What Happens To Your Premium After A Claim

  • A non-fault claim can still raise your renewal, even with 9+ years no-claims.
  • A fault claim normally cuts your no-claims discount, often by two years.
  • Protected no-claims saves the discount years, not the final price.
  • No fixed % increase applies UK-wide; it varies by insurer and claim.
  • The UK average motor premium was £560 in Q1 2026 (ABI).

Last updated: November 2026

Written by the Free Price Compare editorial team | Reviewed November 2026

Why does your premium go up after making a claim?

Your premium goes up after a claim because insurers read any claim on your record as evidence of higher future risk, and they price your renewal accordingly. A claim shows the insurer has already paid out on your policy, or that an incident involving you occurred, and statistically a driver who has claimed once is more likely to claim again. The increase is a repricing of risk, not a penalty for using the cover you paid for.

The size of the change depends on the claim type, who was at fault, how much was paid out and whether your insurer recovered its money from the other side. According to the Association of British Insurers (ABI), the average motor premium was £560 in Q1 2026, roughly 0.2% up on the previous quarter, with high repair costs still a key pressure on prices. A claim adds to that baseline because it raises your individual risk rating within the insurer’s model.

There is no verified UK-wide percentage for how far a premium rises after a claim. Figures quoted elsewhere are not confirmed by any regulator, the ABI or the Financial Ombudsman, so treat any fixed “20% to 50%” type claim with caution. The honest answer is that the effect varies from a modest rise to a large one, and the only reliable way to see it is to compare your renewal against fresh quotes.

What happens to your no-claims discount after a claim?

Your no-claims discount usually falls after an at-fault claim unless you have paid to protect it. A no-claims discount is a reduction applied to your premium for each consecutive year you drive without making a claim. Allianz says its no-claims discount can be around 30% after one claim-free year and up to 60% or more after five years, although discounts vary between insurers and depend on individual circumstances.

According to the Financial Ombudsman Service, a fault claim is likely to reduce your no-claims bonus if it has not been protected, and a two-year reduction is a common arrangement. That is not a universal rule: your policy wording decides exactly how the reduction is applied, and insurers differ, so always check the terms. A no-claims discount that drops from five years to three, for example, can move you to a lower discount tier and increase the price on top of any risk-based repricing.

No-claims history matters to a lot of drivers who compare with us. Around a third of Free Price Compare car insurance quotes come from drivers with zero years of no-claims bonus, while roughly 16% to 19% have 20 or more years built up (Free Price Compare data, Jan-Jun 2026). If you have spent years earning your discount, understanding how a single claim can affect it is worth doing before you decide whether to claim at all.

Compare car insurance quotes in minutes

Will my no-claims discount reset after a claim?

A claim does not usually wipe your no-claims discount to zero; it more often steps it back by a set number of years. A fault claim without protection commonly reduces the discount by around two years, according to Financial Ombudsman guidance, though the exact reduction is governed by your policy wording. So a driver with nine years could drop to seven, rather than losing the lot, depending on the insurer.

Policies often allow a limited number of claims before your protected discount is affected. MoneyHelper notes a common arrangement lets you make one claim in a year, or two claims in three years, while keeping a protected no-claims discount. That allowance protects the discount entitlement only; it does not stop the overall premium rising, so your renewal can still cost more even when the discount stays intact.

Multiple claims in quick succession can have a larger effect than a single one. If you breach the claim limit your policy allows, you can lose discount years and face a higher risk rating at the same time. Reading the no-claims section of your policy document before you claim tells you exactly where you stand.

Does a non-fault claim affect your premium?

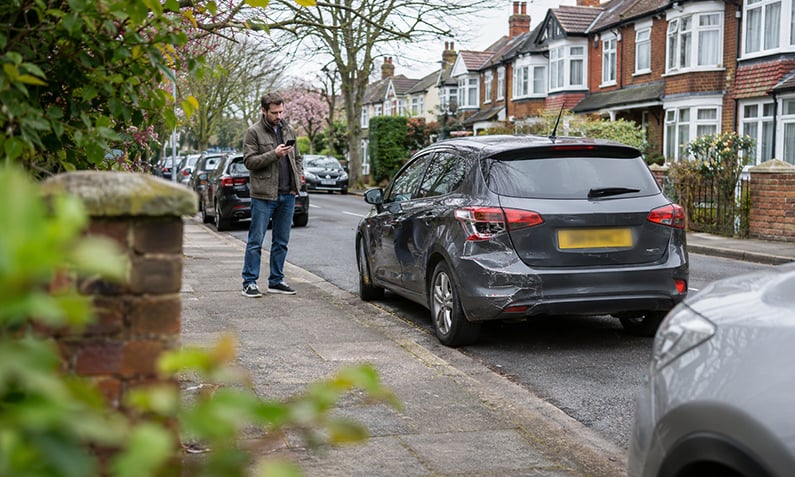
A non-fault claim can still raise your premium at renewal, even though it should not reduce your no-claims discount. Allianz guidance explains that a non-fault claim should not affect the no-claims discount where the insurer recovers its costs from the responsible party, but the previous claim can still be considered in future pricing. In other words, the discount is protected but the base price can move.

Insurers raise prices after non-fault claims because their data shows that a driver who has been involved in one incident is statistically more likely to be involved in another, regardless of blame. The claim also sits on your record through the Claims and Underwriting Exchange, a shared industry database insurers check when they price your cover. That is why a driver who did nothing wrong, and whose insurer recovered every penny, can still see a higher renewal.

If your premium jumps sharply after a non-fault claim, it is worth testing the market rather than accepting the renewal. A useful check is to compare your renewal price against fresh quotes each year, so you can see how far the claim has moved your price relative to the wider market. Our guide on making a car insurance claim in the UK explains the recovery process in more detail.

Does a non-fault claim affect your premium

See if a better price is out there

Compare across 130+ UK insurers and check whether your post-claim renewal is still competitive.

Does protected no-claims stop your premium going up?

Protected no-claims does not stop your premium going up; it only protects the number of discount years you have earned. The Financial Ombudsman Service is clear that protection may preserve the no-claims years after a claim, but the insurer can still increase the underlying price at renewal. This is one of the most common misunderstandings drivers have about protected no-claims.

The distinction matters because the discount is applied to the base premium, and the base premium can rise. If your insurer lifts the underlying price by more than your protected discount saves, your total renewal still goes up. A protected discount is useful insurance against losing years of claim-free status, but it is not a price guarantee, and it does not freeze your renewal.

Deciding whether to pay for protection depends on how much your no-claims discount is worth and how close you are to the top tier. For a driver with many years built up, protecting the discount can be worthwhile, but always weigh the extra cost against what you would realistically save. Comparing cover with and without protection side by side is the clearest way to judge the value.

How does your excess affect what you pay and claim?

Your car insurance excess is the amount you agree to pay towards a claim before your insurer covers the rest. It comes in two parts: a compulsory excess set by the insurer, and a voluntary excess you choose when you set up the policy. Together they make up the total you contribute to any claim, and they directly affect both your premium and whether a small claim is worth making.

Choosing a higher voluntary excess usually lowers your premium, because you are agreeing to shoulder more of any claim yourself. The trade-off is that you pay more out of pocket when you do claim, so the right level depends on how much you could comfortably afford after an accident. Setting a voluntary excess you could not actually pay defeats the purpose, because you still have to find that money before a repair goes ahead.

Excess also shapes the claim decision itself. If the cost of a repair is close to your total excess, claiming may cost you more in the long run once a higher renewal and any lost discount are factored in. Running the numbers before you claim, repair cost versus excess plus the likely premium effect, often shows that paying for a minor dent yourself is the cheaper route.

Set your excess and compare prices

What happens to your premium if your car is written off?

If your car is written off, your insurer treats it as a total loss, pays you the market value minus any excess, and the claim is recorded like any other, which can raise your future premium. A write-off, or total loss, is when the cost of repairs plus the salvage value exceeds the car’s market value, so the insurer settles rather than repairs. The settlement is based on what the car was worth just before the accident, not what you paid for it.

A write-off claim affects your premium in the same way as other claims: it sits on your record, counts towards your claims history and is weighed in your renewal pricing. If the write-off was an at-fault claim and your no-claims discount was not protected, you can expect a reduction in your discount as well. A non-fault write-off, where the other driver was responsible and your insurer recovers its costs, should not reduce a protected discount, though the base price can still rise.

One point catches drivers out: you owe the full annual premium once you have made a claim in the policy year, even if the car is written off and the policy ends. If you pay monthly, the outstanding instalments usually still fall due, because the claim entitles the insurer to the whole year’s premium. If your car was on finance, the settlement may not clear the outstanding balance, so our guide on a car written off on finance explains what to do next.

How long does a car insurance claim stay on your record?

A car insurance claim stays on your insurance record for several years, and insurers ask about recent claims when they quote, typically covering the past five years. Claims are logged on the Claims and Underwriting Exchange, the shared industry database insurers use to verify your history, so you cannot leave a claim off a quote and expect it to go unnoticed. Declaring claims accurately is part of your duty under the Consumer Insurance (Disclosure and Representations) Act 2012.

There is no single universal period that applies to every insurer, claim type or database, so the exact window varies. Most quote forms ask for claims and accidents in the last five years, and a claim’s effect on your price usually fades year by year as it moves further into the past. A claim from four or five years ago generally weighs less than one from last year.

Withdrawing a claim does not reset your record. If you report an incident and then withdraw, you can still be recorded as having made a claim, and your premium may rise regardless. Because of that, it is worth being confident you want to proceed before you notify your insurer of an incident.

Compare renewals against the whole market

How to keep your premium down after a claim

The most effective way to control your premium after a claim is to compare the whole market at renewal rather than accepting the quote your current insurer sends. Insurers weigh claims differently, so a price that looks high with one provider can be noticeably lower with another, and the only way to know is to compare. We let you check cover across a panel of 130+ insurers, and a quote takes only a few minutes, with around 8 in 10 of our car insurance journeys completed on mobile (Free Price Compare data, Jan-Jun 2026).

Beyond comparing, several practical steps can help:

  • Review your voluntary excess; a higher excess can lower the premium, but only set a level you could pay after a claim.
  • Keep your mileage and job details accurate and up to date, as both feed into your price.
  • Consider whether paying annually rather than monthly avoids the interest charged on instalments.
  • Weigh up protecting your no-claims discount if you have several years built up, remembering it protects the discount, not the final price.
  • For very small repairs, compare the cost of paying yourself against claiming and losing discount years.

If you are early in your driving career, the effect of a claim can feel heavier because you have less no-claims history to cushion it. Young drivers aged 17 to 25 make up a larger share of our quotes than of sales, reflecting how price-sensitive that group is. Whatever your age, our guide on the best car insurance for claims in the UK and the wider car insurance claims trends can help you decide what to prioritise.

How to keep your premium down after a claim

FAQs about premium after a claim

How much does car insurance go up after a claim?

There is no fixed UK-wide amount, because the increase depends on the claim type, who was at fault, how much was paid out, your insurer and your wider risk profile. A non-fault claim where the insurer recovers its costs usually has a smaller effect than an at-fault claim. The only reliable way to see the impact is to compare your renewal against fresh quotes from other insurers.

Does a non-fault claim affect my premium?

Yes, a non-fault claim can still raise your premium at renewal, even though it should not reduce a protected no-claims discount where the insurer recovers its costs. Insurers consider any claim on your record when pricing, because a driver involved in one incident is statistically more likely to be involved in another. The claim is logged on a shared industry database that insurers check when they quote.

Does protected no-claims stop my premium going up?

No. Protecting your no-claims discount preserves the number of discount years you have earned, but it does not stop your insurer increasing the underlying price at renewal. If the base premium rises by more than your protected discount saves, your total renewal still goes up. Protection is a safeguard for your discount years, not a price guarantee.

How many claims am I allowed in a year?

Policies differ, but a common arrangement lets you make one claim in a year, or two claims in three years, while keeping a protected no-claims discount. That allowance protects the discount entitlement only, so your premium can still rise at renewal. Always check your own policy wording, because insurers set their own limits.

How long does a car insurance claim stay on my record in the UK?

Most insurers ask about claims and accidents in the past five years when they quote, and claims are logged on a shared industry database. There is no single universal period that applies to every insurer or claim type. A claim’s effect on your price usually lessens year by year as it moves further into the past.

Does withdrawing a claim stop my premium rising?

Not necessarily. If you report an incident and then withdraw the claim, you can still be recorded as having made a claim, and your premium may rise regardless. Because of this, it is worth being confident you want to proceed before you notify your insurer of an incident.

Do I still have to pay the premium if my car is written off?

Yes. Once you have made a claim in the policy year, the insurer is generally entitled to the full annual premium, even if the car is written off and the policy ends. If you pay monthly, the outstanding instalments usually still fall due. The write-off settlement is typically paid as the car’s market value minus your excess.

Should I claim for a small repair or pay for it myself?

If the repair cost is close to your total excess, paying yourself is often cheaper once you factor in a higher renewal and any lost no-claims discount. Run the numbers before you claim: compare the repair cost against your excess plus the likely premium increase. For minor dents and scratches, settling privately frequently works out better.

Why does my premium rise even when I wasn’t at fault?

Insurers price on statistical risk, and their data shows a driver involved in any incident is more likely to be involved in another, regardless of blame. The claim also sits on your record, so future insurers can see it. That is why a non-fault claim, even one where your insurer recovered every penny, can still lift your renewal price.

Is it worth switching insurer after a claim?

Often, yes. Insurers weigh claims differently, so a price that looks high at renewal with one provider can be lower with another. Comparing the whole market at renewal is the single most effective way to control your premium after a claim. A full comparison takes only a few minutes.

How does my excess affect my premium after a claim?

Choosing a higher voluntary excess usually lowers your premium, because you agree to pay more towards any claim yourself. After a claim, your excess is deducted from the payout, so a very high excess reduces what you receive. Set a voluntary excess you could afford to pay if you needed to claim.

Also Read Related Articles


Information correct as of 3 November 2026. Prices, tariffs, policy details and providers change frequently, so please check the latest details before making a decision. This article is for general information only and does not constitute financial advice. Free Price Compare is authorised and regulated by the Financial Conduct Authority (FCA).

4000+ reviews