


Car Insurance Repairs

Written by Ankit Sureja
Reviewed by Tim Bailey
6 min read
Updated: 30 Sep 2026
Car Insurance Repairs

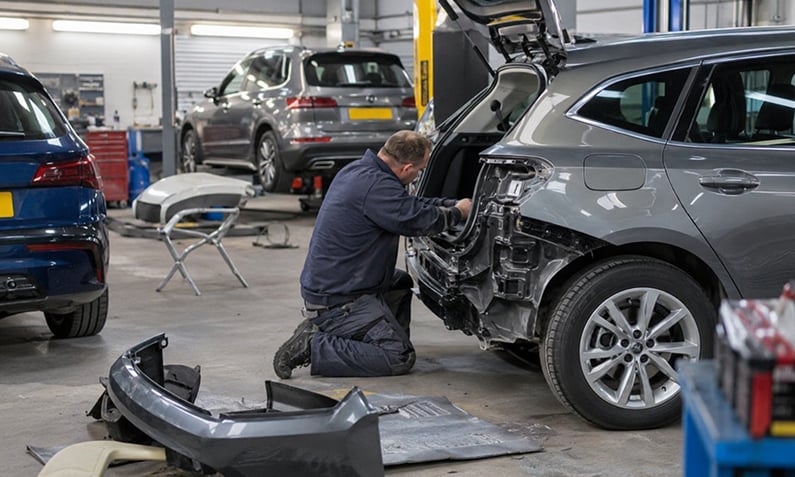
Car insurance repairs are covered only under certain policy types and claim circumstances, not automatically on every policy. Comprehensive cover generally pays to repair your own car after an accident, while third-party only and third-party, fire and theft policies do not cover repairs to your own vehicle. That distinction matters, because around 88-89% of car insurance quotes we see are for comprehensive cover, and most drivers assume it covers more than it actually does.

Car insurance is designed for sudden, one-off damage from events like collisions, fire, theft and vandalism, not for maintenance, wear and tear or mechanical breakdown. So a policy that pays out after you reverse into a bollard will usually decline a claim for a failed clutch or a worn timing belt. Knowing where that line sits helps you decide when to claim, when to pay privately, and what to check before you buy.

We compare car insurance from a panel of 130+ insurers, and this explainer sets out exactly what repairs are and are not covered, how your excess and no-claims bonus affect the decision, and what happens when repairs cost more than your car is worth.

Quick Answer: Car Insurance Repairs

  • Comprehensive cover pays for your own car’s accident repairs; third-party does not
  • Insurance does not cover mechanical breakdown, wear and tear or servicing
  • You pay your excess before the insurer covers the rest of a repair claim
  • If repairs exceed the car’s market value, insurers usually write it off and pay that value
  • Motor insurers paid out £11.9 billion across 2.5 million claims in 2025 (ABI)

Last updated: September 2026

Written by the Free Price Compare editorial team | Reviewed September 2026

Which policies actually pay for repairs to your car?

Only comprehensive car insurance pays to repair your own vehicle after an accident you caused. Third-party only cover pays for damage and injury to other people and their property, but never for repairs to your own car. Third-party, fire and theft adds cover for your car if it is stolen or catches fire, but still does not pay to repair accident damage you are responsible for.

This is the single most important thing to check before you buy. If you pick a cheaper policy to save money, you may be leaving your own car’s repair costs entirely on yourself. Among the quotes we run, around 6% are for third-party only and around 5% for third-party, fire and theft, so a small but real group of drivers hold cover that would not pay for their own repairs after a crash.

Cover level Repairs to your own car (your fault) Damage to others Fire & theft
Third-party only No Yes No
Third-party, fire & theft No Yes Yes
Comprehensive Yes Yes Yes

If you are unsure which level you hold or need, our guide to the different car insurance types and which is right for you breaks down the trade-offs in plain terms.

Compare comprehensive car insurance quotes

Will car insurance cover repairs if the accident was your fault?

Yes, comprehensive car insurance covers repairs to your own car when the accident is your fault, provided you pay your excess first. The Financial Ombudsman Service confirms that under most comprehensive policies, insurers usually arrange and pay for the repairs themselves. If you hold third-party only or third-party, fire and theft cover, your own repairs are not covered when you are at fault.

A car insurance excess is the amount you agree to pay towards a claim before your insurer covers the rest. You will usually pay both a compulsory excess set by the insurer and any voluntary excess you chose to lower your premium. If your repair bill is close to your total excess, claiming may not be worthwhile once you factor in a possible loss of your no-claims bonus.

A no-claims bonus is a discount insurers give for each consecutive year you do not make a claim, and an at-fault claim usually reduces it unless you have protected it. Weigh the repair cost against your excess plus the value of the discount you could lose before deciding to claim.

Will insurance cover repairs if you are not at fault?

If another driver is at fault, their insurer is normally responsible for the full cost of repairing your car, and you should not have to pay an excess in the long run. Citizens Advice notes that with comprehensive cover you can usually claim from your own insurer after an accident, and your insurer then recovers the cost from the other driver’s insurer. If they cannot recover those costs, you may lose your no-claims bonus even though the crash was not your fault.

You can also pursue what are called uninsured losses directly from the at-fault driver’s insurer. According to Citizens Advice, these can include your policy excess, alternative transport while your car is being repaired, loss of earnings and personal injury costs. Adding motor legal cover to your policy can help you recover these amounts if the other side disputes liability.

To protect your position, gather the other driver’s details, take photos at the scene and report the incident to your insurer promptly, even if you do not intend to claim on your own policy.

Will insurance cover repairs if you are not at fault

Not sure your cover is right?

Compare quotes from 130+ UK insurers in about five minutes

Does car insurance cover mechanical repairs or breakdown?

Car insurance does not cover mechanical repairs, engine failure, gearbox faults or general breakdown, because these are treated as wear and tear rather than sudden accidental damage. A comprehensive policy pays for one-off events like collisions, fire, theft and vandalism, not for parts that fail through age or use. So a seized engine, a slipping clutch or a failed gearbox would normally be rejected as a claim.

To cover mechanical or electrical failure you need a separate product, either Mechanical Breakdown Insurance (MBI) or a manufacturer or third-party warranty. Roadside recovery is different again and is provided by breakdown cover, which gets you moving after a fault but does not pay for the repair itself.

There is a narrow exception. If a garage damages your car through proven negligence during a service or repair, that is a dispute with the garage rather than a routine insurance claim, and Citizens Advice sets out your consumer rights when there is a problem with a car repair. Your own comprehensive policy is unlikely to pay for damage caused by a third party’s poor workmanship, though your legal cover may help you pursue the garage.

Can you claim for repairs without an accident?

Yes, you can claim for repairs without a collision if the damage comes from an insured event such as fire, theft, attempted theft, vandalism, storm or flood, provided you hold comprehensive cover. What you cannot claim for is damage from neglect, corrosion, wear and tear or a mechanical fault, because these fall outside what car insurance is designed to cover. So a car keyed in a car park is claimable; a rusted sill or a worn brake disc is not.

Windscreen damage sits in its own category. Most comprehensive policies include glass cover with a lower, separate excess, and a chip repair often costs less than the excess anyway. Windscreen work is getting pricier because modern glass holds cameras and sensors for driver-assistance systems, with the ABI reporting average windscreen repair costs of around £283 in Q2 2026. Our guide to windscreen cover on comprehensive policies explains how the separate glass excess works.

Does car insurance cover pothole damage?

Car insurance can cover pothole damage to your own car if you hold comprehensive cover, since the impact is treated as accidental damage. Whether it is worth claiming depends on the repair bill against your excess and the effect on your no-claims bonus, because pothole damage is often a single wheel, tyre or tracking issue that costs little more than the excess.

You may be able to claim compensation directly from the highway authority responsible for the road instead of using your policy. This route avoids touching your no-claims bonus, but authorities can defend claims if they show they had a reasonable inspection and repair regime in place. Our guide to potholes and their impact on drivers and insurance walks through how to document the damage and pursue a council claim.

See car insurance cover levels compared

What happens if repairs cost more than your car is worth?

If repairs cost more than your car’s value, the insurer will usually declare it a write-off and pay you the vehicle’s market value rather than pay to repair it. Citizens Advice confirms that where repair is not economical, the insurer should offer the car’s market value, which is what it would cost to buy an equivalent vehicle just before the incident. Your excess is normally deducted from that settlement.

The policy terms give the insurer the right to decide whether to repair or write off the car, so you cannot force a repair simply because you want to keep the vehicle. If the settlement figure feels low, you can challenge it with evidence of comparable cars for sale, and escalate to the Financial Ombudsman Service if you cannot agree. Insurers assess this economically: if repair costs fall below the market value, they will usually repair rather than write off.

Some drivers ask to keep a written-off car as a salvage retention. This is often possible, but the insurer deducts the salvage value from your payout, and a Category S or N marker will stay on the vehicle’s record.

Should you claim, arrange your own repairs, or take cash?

Whether to claim, pay privately or accept a cash settlement depends on the repair cost, your excess and the value of your no-claims bonus. For minor damage, paying privately often works out cheaper once you account for your excess and the discount an at-fault claim can cost you at renewal. For a serious repair or a write-off, claiming almost always makes sense.

Key points to weigh before deciding:

  • Compare the likely repair bill against your total excess, both compulsory and voluntary.
  • Factor in the loss of your no-claims bonus and a possible premium rise at renewal if the claim is at fault.
  • Check whether your policy lets you use your own repairer or requires an approved garage, as Citizens Advice notes insurers may insist on an approved repairer and may inspect the car first.
  • If someone else damaged your parked car, their insurer is responsible for the full repair cost, so a claim usually costs you nothing.

Repair timing is also worth considering. The FCA reported in its 2025 motor insurance claims analysis that average lead times before repairs start have more than doubled and repair times have risen by around 36%, so a claim may leave you without your car for longer than you expect. If you rely on your vehicle daily, check whether your policy includes a courtesy car.

How much are drivers paying, and does claiming raise your premium?

The average UK comprehensive motor premium was £560 in Q1 2026, up 0.2% on the previous quarter, according to the ABI Motor Insurance Premium Tracker. A repair claim does not automatically raise your premium, but an at-fault claim typically reduces your no-claims bonus and can push your renewal price up, whereas a non-fault claim your insurer fully recovers should have less impact.

Motor insurers paid out £11.9 billion across 2.5 million claims in 2025, according to the ABI, and a separate trade report citing ABI data put average claim payouts at around £4,900 in Q2 2026. Rising repair complexity, particularly around sensors and cameras in modern vehicles, keeps pushing these costs up, which feeds back into premiums across the market.

Because pricing varies so widely between insurers, comparing at renewal is the most reliable way to keep costs down. Our checklist of questions to ask when comparing car insurance quotes helps you check that the repair terms, excess and courtesy car cover actually suit you before you commit. Around 8 in 10 of the car insurance journeys we handle now happen on mobile (Free Price Compare data, Jan-Jun 2026), and a full comparison across our panel takes about five minutes.

How much are drivers paying, and does claiming raise your premium

Compare car insurance and check what’s covered

FAQs about car insurance repairs

Does my car insurance cover repairs to my own car?

It depends on your cover level. Comprehensive car insurance covers accident repairs to your own car after you pay your excess, while third-party only and third-party, fire and theft policies do not. Check your policy schedule to confirm which level you hold before assuming your own repairs are covered.

Does car insurance cover engine or gearbox failure?

No. Car insurance does not cover engine failure, gearbox faults or other mechanical breakdown, because these are treated as wear and tear rather than sudden accidental damage. To cover mechanical or electrical failure you need separate Mechanical Breakdown Insurance or a warranty, and breakdown cover only pays for recovery, not the repair itself.

Will insurance pay for repairs if the accident was my fault?

Yes, if you hold comprehensive cover, your insurer will usually arrange and pay for the repairs to your own car after you pay your excess. An at-fault claim normally reduces your no-claims bonus unless it is protected. Third-party only and third-party, fire and theft policies will not pay for your own repairs when you are at fault.

Can I claim on insurance for repairs if I was not in an accident?

Yes, if the damage came from another insured event such as fire, theft, vandalism, storm or flood and you hold comprehensive cover. You cannot claim for damage from wear and tear, corrosion, neglect or mechanical faults. Windscreen chips are usually covered under a separate glass excess that is often lower than your main excess.

Can I arrange my own repairs and claim the cost back?

Sometimes, but many insurers require you to use an approved repairer and may inspect the car and request estimates before work begins. If you use your own garage without agreement, the insurer may only pay up to what its approved network would have charged. Always check your policy and get approval before commissioning repairs.

What happens if repairs cost more than my car is worth?

The insurer will usually write the car off and pay you its market value rather than pay for uneconomical repairs, with your excess deducted. You can challenge a low valuation with evidence of comparable cars for sale. You may also be able to keep the written-off car as salvage, though the salvage value is deducted from your payout.

Will car insurance cover repairs if someone else was driving my car?

It depends on whether that person was insured to drive your car. If they were named on your policy or had their own valid cover to drive it, your comprehensive policy can pay for repairs after an at-fault accident. If they were not insured to drive your car, the claim may be refused and you could be liable for the costs.

Is it worth claiming for minor repairs?

Often not. For small repairs, the cost may be close to or below your total excess, and an at-fault claim can reduce your no-claims bonus and raise your renewal price. Compare the repair quote against your excess and the value of the discount you would lose before deciding to claim or pay privately.

Should I go through insurance or accept a cash offer from the other driver?

Accepting cash can save the other driver a claim, but it leaves you exposed if the damage is worse than it looks or if they refuse to pay once you have committed. Going through insurance gives you a formal record and protection if hidden damage emerges. If you suspect the repair could exceed a few hundred pounds, a claim is usually safer.

How long does a car repair take after an insurance claim?

Repair times have lengthened across the market. The FCA reported in its 2025 review that average lead times before repairs start have more than doubled and repair durations have risen by around 36%, partly due to parts availability and vehicle complexity. Ask your insurer whether your policy includes a courtesy car if you rely on your vehicle.

Will making a repair claim increase my premium?

Not automatically. An at-fault claim typically reduces your no-claims bonus and can push your renewal price up, while a non-fault claim your insurer fully recovers from the other party should have less impact. Because insurers price claims history differently, comparing quotes at renewal is the best way to limit any increase.

Also Read Related Articles


Information correct as of 28 September 2026. Prices, tariffs, policy details and providers change frequently, so please check the latest details before making a decision. This article is for general information only and does not constitute financial advice. Free Price Compare is authorised and regulated by the Financial Conduct Authority (FCA).

4000+ reviews