


Converted Campervan Insurance Explained

Written by Tim Bailey
Reviewed by Prajesh Manvar
6 min read
Updated: 17 Sep 2026
Converted Campervan Insurance Explained

Converted campervan insurance is a specialist motor policy that covers a van you have turned into a living space, insuring both the vehicle and the conversion work rather than just a bare panel van. It is a legal requirement to have at least third-party cover to drive or park on UK public roads under the Road Traffic Act 1988, but standard van insurance rarely values your conversion correctly, which can leave you badly under-insured after a claim.

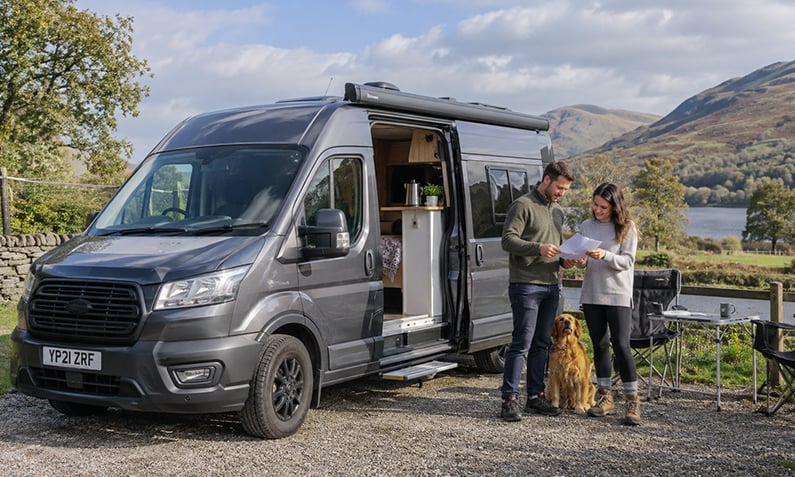
If you have fitted out a Transit, a VW Transporter or another van with a bed, kitchen and gas, you need cover that recognises the build value and, ideally, pays an agreed figure if the vehicle is written off or stolen. Free Price Compare works with a panel of 63 van insurance providers, including specialists who understand conversions, so you can match the right class of use to a fair price.

Below is a plain-English breakdown of what these policies cover, what they typically cost in 2026, the proof insurers ask for, and how the DVLA reclassification process affects your quote.

Quick Answer: Converted Campervan Insurance Explained

  • Agreed value cover is the key feature for a conversion: it sets an insured sum with your insurer up front, so a total-loss payout reflects the build rather than the bare van’s market value.
  • Insurers usually ask for proof of conversion: dated build photos, receipts for major fittings and sometimes an independent valuation for higher-value builds.
  • You do not always have to reclassify on the V5C to insure a conversion, but the DVLA’s motor caravan body-type change can widen your choice of specialist insurers.
  • Main cost drivers are build value, whether it is DIY or professional, annual mileage, overnight storage and security, plus the driver’s age and claims history.
  • Standard van or car insurance rarely covers the conversion’s contents or full value, so a self-built camper on a bare-van policy risks a shortfall at claim time.

Last updated: September 2026

Written by the Free Price Compare editorial team | Reviewed September 2026

What does converted campervan insurance actually cover?

Converted campervan insurance covers your legal liability to others, damage to the vehicle, and the value of the fitted conversion, with the exact protection depending on the cover level you choose. A policy written for a conversion treats the bed, cabinetry, cooker, water system and electrics as part of the insured vehicle, whereas ordinary van insurance treats them as irrelevant to the van’s value.

The three standard cover levels apply here just as they do to any vehicle. Third-party only is the legal minimum and pays for injury or damage you cause to others. Third-party, fire and theft adds protection if the van is stolen or catches fire. Comprehensive is the widest option and also pays for accidental damage to your own vehicle.

  • Agreed value: you and the insurer fix an insured sum up front, so a write-off pays that figure rather than a disputed market value.
  • Contents and personal possessions: cover for cooking equipment, awnings and personal items, often with a set limit you can increase.
  • Public liability and European use: useful if you travel abroad or park up on private land.

For higher-value builds, an insurer may also offer new-for-old on recent fittings. If your van still runs partly as a work vehicle, check the class of use carefully so you are covered for both leisure and any business mileage.

Compare converted campervan cover

How much does converted campervan insurance cost in 2026?

Converted campervan insurance in 2026 commonly costs between around £250 and £1,200 a year, with many home conversions on comprehensive agreed-value cover landing in the mid-range. The wide spread reflects how different a small panel-van conversion is from a high-value coachbuilt or a fully fitted VW Transporter.

Specialist 2026 pricing guides give a useful shape to the market. A small VW panel-van conversion can start near £250 to £285, a mid-size van conversion sits around £430, and a large or high-value build can reach £720 or more, with the most valuable conversions exceeding £1,000. VW Transporter conversions tend to price higher because build and vehicle values are often substantial.

Conversion type Indicative annual premium
Small VW / panel-van conversion Around £250 to £300
Mid-size van conversion Around £400 to £450
Large or high-value / coachbuilt Around £700 to £1,200+
Higher-value VW Transporter build (agreed value) Around £700 to £1,300

Figures are indicative and may change. Your own quote depends on the build value you declare, your age and claims history, where the van is kept overnight and how many miles you drive. These figures are drawn from specialist 2026 market guides rather than a regulator, so treat them as a guide, not a promise. For a wider view of costs, see our campervan insurance costs and cover guide.

Will standard van insurance cover my self-converted campervan?

Standard van insurance rarely covers a self-converted campervan properly, because a bare-van policy values the vehicle as an empty panel van and ignores the conversion entirely. If you fit out a Transit or a Transporter and leave it on ordinary van cover, a total-loss payout could fall thousands of pounds short of what you spent on the build.

There are two practical problems. First, the insured value: a van-only policy pays the empty van’s market value, not the value of your bed, kitchen and electrics. Second, contents: many van and car policies cap personal belongings at a low figure such as £100, which does not stretch to a fitted-out camper. That is why modified van insurance or a dedicated conversion policy usually makes more sense once the fit-out is complete.

Some mainstream insurers will decline conversions outright, and a handful will only insure the bare van without the interior. Specialist campervan and conversion insurers are set up for these vehicles and can offer agreed value cover for the whole build, which is the outcome most owners want.

Will standard van insurance cover my self-converted campervan

Insure the whole build, not just the van

Match a conversion policy to your vehicle from our 63-provider panel

What proof of conversion do insurers need?

Insurers assessing a converted campervan usually ask for evidence that the conversion exists and what it is worth, which for most builds means dated photos, receipts and a description of the work. This protects both sides: it lets the insurer set a fair agreed value and gives you a documented claim record if the worst happens.

  • Build photographs: clear, dated images of the interior, fittings, gas and electrical work, ideally showing the stages of the conversion.
  • Receipts and invoices: for major items such as the bed, units, cooker, leisure battery, solar and any professional labour.
  • An independent valuation: often requested for higher-value builds to support the agreed sum insured.
  • Gas and electrical safety records: some insurers ask about a gas safety certificate, and cover for on-board gas fires can be limited on privately converted vehicles, so read the wording.

Keep this evidence organised from the start of your build. A tidy folder of photos and receipts makes it far quicker to get an accurate agreed value and speeds up any future claim.

Get a self-build camper quote

Do I need to reclassify my van on the V5C?

You do not always have to reclassify your van as a motor caravan on the V5C to insure a conversion, but doing so through the DVLA can widen your choice of specialist insurers and better reflect how the vehicle is used. Reclassification changes the recorded body type to “motor caravan”, which some insurers prefer to see before offering their best conversion terms.

The DVLA sets specific criteria for a motor caravan body-type change, covering permanent features such as a bed, seating with a table, storage and cooking or washing facilities, plus external appearance. Meeting those criteria is not guaranteed, and the DVLA can decline a change if the build does not qualify. You can still insure a van that remains classified as a panel van, but you will need an insurer comfortable covering it as a conversion.

Reclassifying can also affect speed limits and, in some cases, MOT arrangements, so weigh it up before applying. Whatever the V5C says, tell your insurer honestly that the vehicle is a conversion used as a camper, as non-disclosure can invalidate cover. For lighter builds, our micro camper van insurance guidance covers day-van conversions that may not meet the full motor caravan definition.

How can I reduce the cost of camper conversion insurance?

The most reliable way to reduce camper conversion insurance is to lower the risk you present, then compare specialist quotes so you are not paying a mainstream insurer’s decline-risk margin. Because build value and usage drive the price, small changes to how you store, secure and use the vehicle can make a real difference.

  • Fit and declare security: alarms, immobilisers, trackers and Thatcham-rated devices can lower premiums, especially on higher-value VW builds.
  • Keep mileage realistic: a limited-mileage policy suits a leisure camper used mainly at weekends and in summer.
  • Improve overnight storage: a driveway, secure compound or locked garage usually beats on-street parking.
  • Build and protect a no-claims bonus: years of claim-free driving carry across to specialist campervan cover.
  • Choose agreed value carefully: declaring an accurate figure avoids overpaying for cover you do not need and prevents a shortfall.

Adding camper van breakdown cover is worth pricing separately rather than assuming it is included, as conversions can be heavier and taller than standard vans. It is also worth comparing whether a conversion is cheaper through a specialist than a mainstream insurer, since specialists often quote where others decline.

Compare VW and conversion quotes

Insuring a build before it is finished

Campervan-in-conversion insurance covers a vehicle while you are still converting it, protecting the van and the work completed so far before the fit-out is finished. This is a distinct product from finished-conversion cover, and not every insurer offers it, so it is worth asking specialist brokers directly.

This matters because a half-built camper is exposed to theft and fire risk while it sits on your drive, often with expensive materials and part-fitted electrics inside. Some policies for an in-progress build are laid-up or limited-use, covering fire, theft and accidental damage but not general road use, so check exactly what you are allowed to do on the policy.

Once the build is complete, tell the insurer so the cover and agreed value can be updated to reflect the finished vehicle. If your project is a professionally built motorhome rather than a self-fit, our motorhome insurance comparison may be the better route.

Insuring a build before it is finished

FAQs about converted campervan insurance

Yes. To drive or park a campervan on UK public roads you must hold at least third-party insurance under the Road Traffic Act 1988. If you keep the vehicle off the road and are not using it, you can declare it off-road with a SORN, but Continuous Insurance Enforcement means an untaxed, uninsured vehicle on a public road can be penalised.

How difficult is it to get insurance for a DIY camper conversion?

It is very possible to insure a DIY conversion, but you usually need a specialist rather than a mainstream insurer, as some will decline home-built vans. Specialist campervan insurers can offer agreed value cover for the full build, including bespoke work, provided you supply photos, receipts and sometimes an independent valuation to support the sum insured.

What is agreed value cover and why does it matter for a conversion?

Agreed value cover means you and the insurer fix the vehicle’s insured sum in advance, so a total-loss claim pays that figure rather than a disputed market value. It matters for conversions because a bare-van market value ignores the money spent on the fit-out, and agreed value protects the true worth of your build.

What should I expect to pay for camper van insurance?

Most converted campervans in 2026 cost roughly £250 to £1,200 a year to insure, with typical home conversions on comprehensive agreed-value cover often around £350 to £600. Your actual price depends on the build value, whether it is DIY or professional, your mileage, security, storage and driving history.

Can I insure a converted campervan without reclassifying it on the V5C?

Yes, you can insure a van that is still classified as a panel van on the V5C, provided you find an insurer willing to cover it as a conversion. Reclassifying to motor caravan through the DVLA can widen your choice of specialist insurers, but the main requirement is to declare honestly that the vehicle is used as a camper.

Will my new conversion be covered straight away or is there a waiting period?

Cover can usually start immediately once an insurer accepts the risk, but some providers apply conditions, such as needing you to have owned the vehicle for a period before offering their best terms. Ask about any such conditions when you get a quote so there is no gap in cover after you finish the build.

Does campervan insurance cover the contents and my personal belongings?

Many conversion policies include contents and personal possessions cover up to a set limit, which you can often increase for an extra premium. This is a key reason not to rely on standard van or car insurance, which may cap personal belongings at a low level, far below the value inside a fitted camper.

Is on-board gas covered by campervan insurance?

Cover for on-board gas can be limited on privately converted campervans, and some policies restrict or exclude loss or damage from a fire connected to the domestic gas supply. Always read the policy wording on gas and consider a gas safety certificate, as this affects both eligibility and any future claim.

Is specialist campervan insurance cheaper than going through a mainstream insurer?

For a conversion, a specialist is often the better and sometimes the only option, because many mainstream insurers decline home-built or heavily modified vans. Specialists price these vehicles routinely and can offer agreed value cover, so it is worth comparing specialist quotes rather than assuming a standard motor insurer will match them.

Can I insure a van while I am still converting it?

Yes, campervan-in-conversion insurance covers the vehicle and the work done so far while the build is in progress, though not every insurer offers it. Some in-progress policies are laid-up or limited-use, covering fire, theft and accidental damage but not full road use, so check what you are permitted to do before relying on it.

Do I need camper van breakdown cover as well as insurance?

Breakdown cover is separate from your insurance and is worth pricing on its own, since converted vans can be heavier and taller than standard vehicles. Choose a provider that recovers larger campervans and covers the routes and countries you plan to travel, as basic policies may not handle a fully loaded conversion.

What happens if my converted campervan is written off?

On an agreed value policy, the insurer pays the sum insured you agreed at the start, so keep that figure accurate and your build evidence up to date. Without agreed value, the payout is based on market value, which for a conversion can be far less than you spent, leaving you out of pocket.

Also Read Related Articles


Information correct as of 13 September 2026. Prices, tariffs, policy details and providers change frequently, so please check the latest details before making a decision. This article is for general information only and does not constitute financial advice. Free Price Compare is authorised and regulated by the Financial Conduct Authority (FCA).

4000+ reviews