


Admiral Multi Van Insurance: How It Works

Written by Tim Bailey
Reviewed by Prajesh Manvar
6 min read
Updated: 30 Sep 2026
Admiral Multi Van Insurance: How It Works

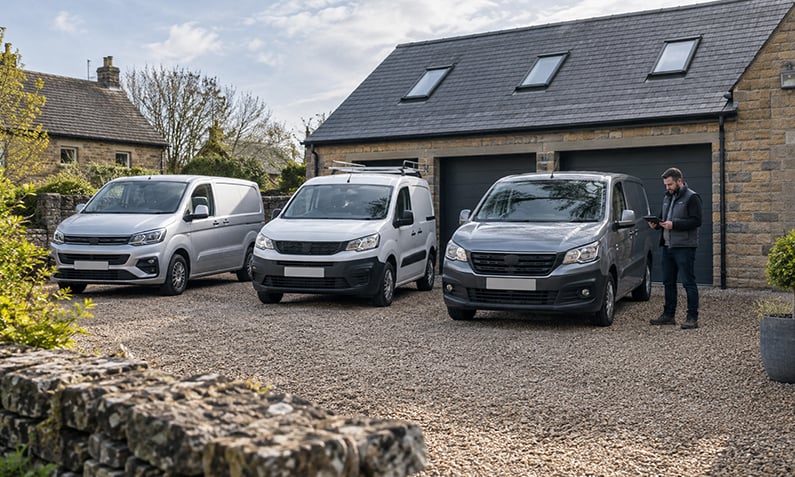
Admiral multi van insurance lets you cover up to seven vans on one policy, with one renewal date and a discount for each van you add. It suits sole traders, tradespeople and small businesses that run several vehicles and want to stop juggling separate policies and staggered renewal dates.

You can insure up to seven vans on one Admiral multi van policy, and it does not matter whether you use some for business and others for leisure. Each van can have its own named drivers and its own class of use, so a work van set up for carriage of own goods and a second van used only for social, domestic and pleasure can sit on the same policy.

Free Price Compare is FCA-authorised and compares van cover from a panel of 63 providers, so this explainer sticks to what the product actually does, how the price is built and what to check before you commit, rather than pushing a single insurer.

Quick Answer: Admiral Multi Van Insurance

  • Admiral lets you insure up to seven vans on one multi van policy, with one renewal date and a discount for each van added.
  • Cover comes in three levels: comprehensive, third-party fire & theft, and third-party only; Admiral, Gold and Platinum comprehensive tiers hold Defaqto’s highest 5-star rating.
  • Each van can carry its own class of use and its own named drivers, so business and social use can mix on one policy.
  • By class of use, Q1 2026 average van premiums were around £723 for social use and £860 for business use (van insurance price index data).
  • Van insurance is legally required under the Road Traffic Act 1988 and checked against the Motor Insurance Database, so every van on the policy must be individually recorded.

Last updated: September 2026

Written by the Free Price Compare editorial team | Reviewed September 2026

What Admiral multi van insurance actually covers

Admiral multi van insurance groups several vans onto one policy while keeping each vehicle’s cover, drivers and class of use separate. You choose a cover level for each van, add the drivers who use it, and set the correct class of use, then everything renews on the same date. Admiral covers single cab, double cab, lifestyle and commercial pick-ups, along with vans up to 3.5 tonnes, which is the weight limit most people can drive on a standard category B driving licence.

Three cover levels are available. Comprehensive is the highest, and Admiral’s comprehensive tiers named Admiral, Gold and Platinum hold the highest 5-star rating from Defaqto. Third-party fire & theft covers damage or injury you cause to others plus fire and theft of your own van, while third-party only is the legal minimum and does not pay for damage to your own vehicle. Admiral’s comprehensive van policies sold since February 2019 include vehicle replacement cover as standard on the higher tiers, though not on the Essential level.

Windscreen repair, a courtesy van and European cover feature on the comprehensive tiers. European driving is generally covered for up to 90 days, which matters if any van crosses the Channel for work.

Compare multi van cover across 63 providers

How many vans can I insure on one policy?

You can insure up to seven vans on one Admiral multi van policy. Each van sits under the same renewal date, which removes the task of tracking several separate expiry dates through the year. A discount is applied for each van you add, and you set the cover level and named drivers per vehicle rather than applying one blanket setup to the whole group.

A multi van policy is different from a traditional fleet policy. Fleet cover usually applies one set of terms across every vehicle and is aimed at larger operators, whereas a multi van arrangement keeps each van’s details individual while combining them for admin and pricing. If you run more than seven vans, or want any-driver terms across the whole group, a dedicated fleet product is likely the better route. Our guide to multi van insurance and how fleet cover compares sets out where each option fits.

Is multi van insurance cheaper than separate policies?

Multi van insurance is often cheaper than buying separate single-van policies because each added van attracts a discount and you avoid duplicate administration. The saving is not guaranteed for every driver, though, so the only reliable way to know is to compare the combined multi van price against the total of individual quotes for the same vans, drivers and cover levels.

Whether a multi van policy wins depends on the mix of vehicles and drivers. If one van is high risk, for example driven by a younger tradesperson or based in a higher-risk postcode, bundling it with lower-risk vans can sometimes push the combined price up rather than down. Run both scenarios before deciding. Our guides on whether you are overpaying for van insurance and cutting your van insurance costs explain the checks worth running each year.

Not sure a bundle beats separate policies?

Compare a multi van price against individual quotes side by side.

What affects the price of my premium?

Van insurance premiums are built from the risk each van and driver represents, so age, driving history, postcode, annual mileage, the van itself and the class of use all feed the price. By class of use, van insurance price data shows social-use and business-use policies usually cost less than younger-driver policies, while the cheapest policies sit well below the average market rate.

Class of use is the single detail most often set wrongly. Social, domestic and pleasure covers personal use only. Carriage of own goods covers tools and materials for your own trade. Carriage of goods for hire and reward, such as courier or delivery work, sits at the top of the price range. According to the Association of British Insurers (ABI), motor insurers paid out record sums in 2026 as claims costs stayed high, which keeps upward pressure on premiums across the market.

  • Class of use: social only, carriage of own goods, or hire and reward.
  • Driver age, licence type and claims history for each named driver.
  • Van value, engine size, weight and how easily it is stolen.
  • Overnight parking location and business postcode.
  • Annual mileage and whether the van carries valuable tools.

Getting the class of use wrong can invalidate a claim, so declare it accurately even if a lower category looks cheaper. If your work van doubles as a family runaround at weekends, tell the insurer.

What affects the price of my premium

Get an Admiral van insurance quote comparison

Does every driver need to be named on the policy?

Every person who drives a van on the policy must be covered, and on a multi van policy you can name different drivers against each van rather than giving everyone access to every vehicle. Adding a driver who is not named, or letting an uninsured person drive, breaches the terms and can leave a claim rejected.

Named drivers let you match the right people to the right vans, which helps the price when a lower-risk vehicle avoids being loaded with a higher-risk driver’s record. If a driver only occasionally uses another firm’s van, check whether they have driving-other-vehicles cover, though this is rarely included on van policies and usually only extends to third-party cover on cars where it exists at all. Our explainer on driving someone else’s vehicle covers when that extension applies.

How does the no-claims bonus work on multiple vans?

A no-claims bonus is a discount insurers give for each consecutive year you do not make a claim, and on a multi van policy each van can build and hold its own no-claims record. That means a claim on one van does not automatically wipe out the discount earned on the others, though the exact treatment depends on the policy terms, so confirm this at the quote stage.

Keeping separate no-claims histories per van is one of the practical advantages of a multi van setup over a single all-encompassing fleet policy. If you later split the vans onto different policies, you generally take each van’s earned discount with it. Protected no-claims is sometimes available for an extra cost and limits how much a fault claim reduces the discount, but it does not stop the base premium rising after a claim.

Am I covered to drive in Europe?

Admiral comprehensive van policies generally include European cover for up to 90 days, letting you drive vans on the same level of cover as at home for a set period abroad. Third-party only and third-party fire & theft policies still meet the legal minimum for driving in the EU, but they do not extend your comprehensive protection across the Channel unless the policy states otherwise.

Check the exact number of days and whether any business use abroad is included before you travel, as terms vary by cover tier and by how you use the van. Carry your insurance documents and confirm whether a green card or other paperwork is needed for the countries on your route. If European work is a regular part of the business, raise it at the quote stage so it is written into the policy rather than assumed.

Admiral multi van vs MultiCar and MultiCover

Admiral multi van insurance, MultiCar and MultiCover are three separate products that are easy to confuse. Multi van covers up to seven vans on one policy. MultiCar covers multiple cars on one policy with separate no-claims discounts per car. MultiCover lets you combine different Admiral policies, such as a van and a car, under one account for a single view and potential discount.

Product What it groups Best for
Multi van Up to 7 vans on one policy Traders and small firms running several vans
MultiCar Multiple cars on one policy Households with more than one car
MultiCover Different policy types under one account Owners mixing van, car and home cover

Figures are indicative and may change.

If you want to combine a van and a car rather than several vans, MultiCover is the relevant product, not multi van. Our multi car insurance guide explains the car-side equivalent, and the Admiral comprehensive cover guide covers what the top tiers include.

Paying monthly and premium finance

Paying van insurance monthly usually costs more than paying the full premium in one go, because monthly instalments are a form of credit that carries interest. The Financial Conduct Authority (FCA) published its premium finance market study final report on 3 February 2026 and found interest rates on premium finance had fallen by an average of 4.1 percentage points since 2022, saving consumers around £157m a year, but it did not introduce a price cap.

Check the annual percentage rate (APR) and the total payable, not just the monthly figure, before choosing to spread the cost. If you can pay annually you avoid the interest entirely. Van insurance is legally required under the Road Traffic Act 1988, and every van you own must be either insured or declared off the road under Continuous Insurance Enforcement, so letting cover lapse to save money risks a penalty from the DVLA.

See how van cover compares before you renew

Should you compare before renewing?

Comparing van insurance before you renew is the most reliable way to check your multi van price is still competitive, because insurers reprice each year and loyalty rarely earns the lowest quote. Run the combined multi van figure against separate quotes for the same vans, drivers and cover, and repeat the exercise every renewal rather than auto-renewing.

Free Price Compare checks van cover across a panel of 63 providers, so you can see how an Admiral multi van quote sits against the wider market in one search. Have your van registrations, driver details, class of use and current no-claims years ready, since accurate details produce accurate quotes. Our guide on why UK van insurance costs more than in Europe gives useful context on where the market sits.

Should you compare before renewing

FAQs about admiral multi van insurance

What is Admiral MultiCover insurance?

Admiral MultiCover lets you bring different Admiral policies together under one account, such as a van policy and a car policy, giving you one place to manage them and a potential discount. It is not the same as multi van insurance, which groups several vans on a single policy. MultiCover is about combining different types of cover, whereas multi van is about combining vehicles of the same type.

Can I add a van to my Admiral car insurance?

You cannot add a van to a standard car policy, because vans and cars are rated and covered differently. If you want to hold both with the same insurer, MultiCover lets you keep separate van and car policies under one account rather than merging them into a single policy. Each vehicle keeps its own cover level and no-claims record.

How many vans can I insure on one Admiral policy?

You can insure up to seven vans on one Admiral multi van policy. All the vans share a single renewal date, and a discount is applied for each van you add. If you need to cover more than seven vans, a dedicated fleet policy is usually the more suitable option.

Is Admiral multi van insurance cheaper than separate policies?

It often works out cheaper because of the per-van discount and reduced admin, but it is not guaranteed for every driver. Bundling a high-risk van with lower-risk ones can occasionally raise the combined price. Compare the multi van quote against the total of individual quotes for the same vans and drivers to see which is better value.

Does every driver have to be named on a multi van policy?

Yes, everyone who drives a van on the policy must be covered, and on a multi van policy you can name different drivers against each van. Letting an unnamed or uninsured person drive breaches the terms and can lead to a claim being refused. Matching lower-risk drivers to specific vans can also help keep the price down.

What cover levels does Admiral offer for vans?

Admiral offers comprehensive, third-party fire & theft, and third-party only cover for vans. Comprehensive is the highest level and its Admiral, Gold and Platinum tiers hold Defaqto's highest 5-star rating. Third-party only is the legal minimum and does not pay for damage to your own van.

Am I covered to drive an Admiral-insured van in Europe?

Admiral comprehensive van policies generally include European cover for up to 90 days, keeping the same level of protection you have at home for a set period abroad. Third-party only and third-party fire & theft still meet the legal minimum to drive in the EU but do not extend comprehensive cover across the Channel. Check the exact terms and any paperwork needed before you travel.

What class of use should I choose for my van?

Choose social, domestic and pleasure if the van is for personal use only, carriage of own goods if you carry tools and materials for your own trade, and carriage of goods for hire and reward for courier or delivery work. Hire and reward is the most expensive category. Declaring a lower class than you actually use can invalidate a claim, so be accurate.

Does a claim on one van affect the no-claims bonus on my others?

On a multi van policy each van can usually keep its own no-claims record, so a claim on one van does not automatically wipe out the discount on the others. The exact treatment depends on the policy terms, so confirm it when you get a quote. Protected no-claims can be added for an extra cost to limit the impact of a fault claim.

Is it cheaper to pay for van insurance annually or monthly?

Paying annually is usually cheaper because monthly instalments are a form of credit that carries interest, adding to the total cost. Always check the APR and the total payable, not just the monthly figure. The FCA reported in February 2026 that premium finance interest rates had fallen since 2022, but monthly still costs more than paying in one payment.

What happens if I cancel my multi van policy mid-term?

Cancelling mid-term usually means a cancellation fee plus a charge for the days you were covered, so you rarely get a full refund. If you pay monthly through premium finance, you may also need to settle the outstanding balance. Check the cancellation terms before you commit, and time any switch to line up with your renewal date where possible.

Can I ask Admiral to lower my renewal quote?

You can always contact your insurer to question a renewal price, and comparing the wider market first gives you a benchmark to negotiate with. Renewal quotes are repriced each year and are not always the cheapest available. Running a fresh comparison across multiple providers is the most reliable way to check whether your current price is still competitive.

Also Read Related Articles


Information correct as of 22 September 2026. Prices, tariffs, policy details and providers change frequently, so please check the latest details before making a decision. This article is for general information only and does not constitute financial advice. Free Price Compare is authorised and regulated by the Financial Conduct Authority (FCA).

4000+ reviews