Audi car insurance: cost, groups and cover explained

Written by Brijesh Patel
Reviewed by Pratik Aghera
7 min read
Updated: 12 Nov 2026
Audi car insurance: cost, groups and cover explained

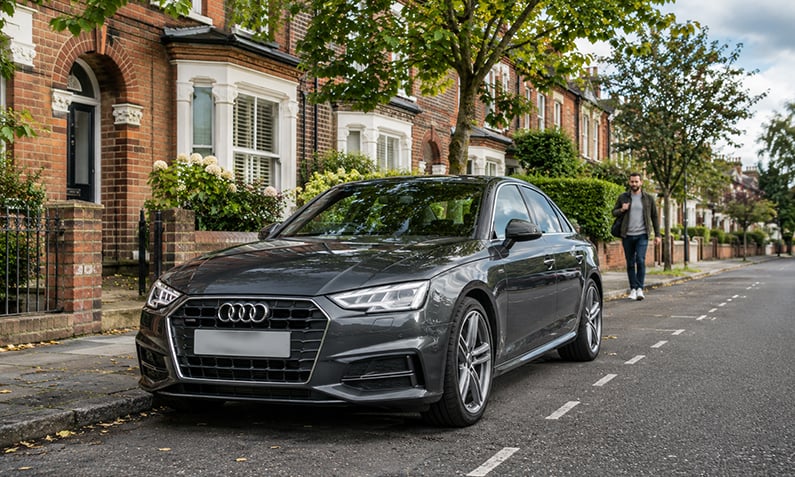
Audi car insurance covers an Audi against accident, fire, theft and damage to other people, with prices set mainly by the model’s insurance group, the car’s value and your own driver profile. There is no single “Audi price”: estimates for 2026 run from around £450-£650 a year for a small Audi A1 up to £2,340-plus for a high-performance RS6 Avant, according to market data published in October 2026.

Audi sits mid-table among the makes quoted through Free Price Compare, roughly level with BMW and Nissan at around 5-6% of quotes. That matters because an Audi is not automatically expensive to insure. A diesel A1 or A3 in a low group can cost less than many mainstream hatchbacks, while an S or RS model in group 45-50 sits at the top end. We compare cover from a panel of 130+ UK insurers, and the gap between the cheapest and most expensive quote for the same Audi is usually where the real saving is.

Quick Answer: Audi car insurance

  • Audi A1 estimates run around £450-£650 a year; A6 around £1,447 (2026 market data)
  • Audi insurance groups span 9 to 50 – the single biggest price driver
  • UK average motor premium was £560 in Q1 2026, down £20 year on year (ABI)
  • S and RS models cost more due to higher power, value and repair costs
  • New alloys and other modifications must be declared or cover can be voided

Last updated: October 2026

Written by the Free Price Compare editorial team | Reviewed October 2026

What drives the cost of Audi car insurance?

The cost of Audi car insurance is driven first by the car’s insurance group, then by its value, repair costs and your own driver profile. Every car sold in the UK is placed in an insurance group from 1 to 50 by the Insurance Group Rating Panel, using data assessed by Thatcham Research. Audi models span almost the full range, from around group 9 for the smallest petrol A1 to group 50 for the RS6 Avant.

A higher group means higher expected claims costs, which feeds directly into your premium. Audi’s premium positioning, aluminium body panels, driver-assistance technology and genuine parts can all make repairs dearer, and the ABI noted in Q1 2026 that repair costs kept rising even as average premiums held steady. The more a car costs to fix or replace, the more it costs to insure.

Your own details then move the price up or down: age, postcode, annual mileage, occupation, claims history and no-claims bonus. The impact of insurance groups on premiums explains how the group rating interacts with these personal factors.

How much does Audi car insurance cost by model?

Audi car insurance cost varies sharply by model and trim, from around £450 a year for a small A1 to over £2,300 for a performance RS model, based on 2026 market estimates. These are indicative figures, not quotes – your own premium depends on your age, address, mileage and history. The table below gives a realistic starting point for the popular ranges.

Audi model Estimated annual premium (2026)
Audi A1 around £450-£650
Audi A3 around £500-£750
Audi A4 around £550-£800
Audi Q2 / Q3 around £600-£850
Audi TT around £650-£950
Audi Q5 / Q7 around £750-£1,100-plus
Audi A6 (typical) around £1,447 (about £125 a month)
Audi S3 / RS3 around £850-£1,200-plus
Audi RS6 Avant £2,340-plus

Figures are indicative and may change.

For context, the UK average private motor premium was £560 in Q1 2026, according to the ABI (Association of British Insurers) – £20 lower than Q1 2025. So a well-chosen small Audi can sit near that average, while a large SUV or performance saloon runs well above it. Around 9 in 10 car insurance quotes we see are for comprehensive cover, which is the level most Audi owners choose.

Compare Audi car insurance quotes

How much is car insurance for an Audi A1?

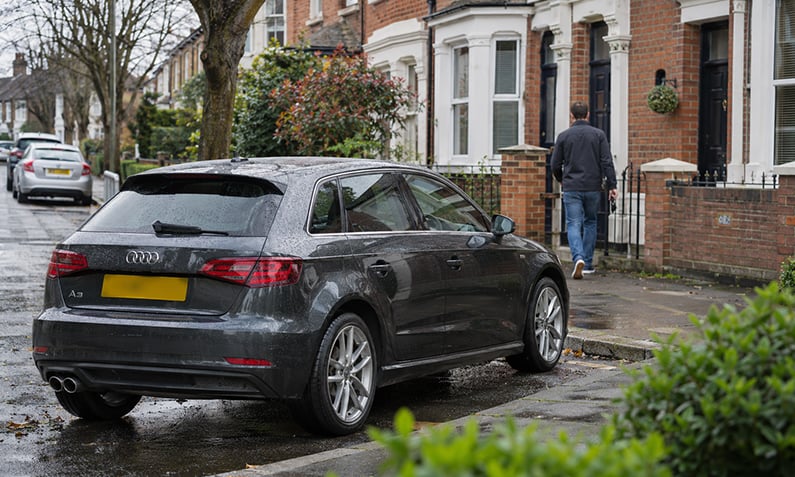
Car insurance for an Audi A1 is estimated at around £450-£650 a year for a typical adult driver, based on 2026 market data, making it one of the cheaper Audis to cover. The A1 sits in some of the lowest Audi insurance groups, which keeps its base cost down. A standard-driver price near the lower end is realistic for an experienced policyholder with a clean record in a low-risk postcode.

The picture is very different for new and young drivers. A 17-year-old insuring an A1 can face premiums several times higher than an older driver’s, because insurers price inexperience as higher risk. Around a third of the car insurance quotes we see come from drivers with zero years of no-claims bonus, and drivers aged 17-25 shop heavily but pay the most. If you are a new driver, a black box insurance policy can reduce the price by rewarding careful driving – our guide for younger drivers explains the options in full.

How much is car insurance for an Audi A1

Why does the Audi A6 cost more to insure?

The Audi A6 costs more to insure than smaller Audis because it is a larger, higher-value car in a higher insurance group, with an estimated comprehensive premium of around £1,447 a year (about £125 a month) on 2026 market data. Premiums for the A6 range widely by variant: roughly £1,180 for a 40 TDI SE in groups 23-24, rising to £1,790 for the 50 TFSI e plug-in hybrid in group 42, and £2,340-plus for the RS6 Avant in group 50.

Three things push the A6 up: its purchase price, its repair complexity and, on higher trims, performance. Plug-in hybrid and quattro versions carry pricier components and sit in higher groups, while S and RS versions add power and value on top. If you are weighing up variants, the group number is the clearest single guide to the likely premium gap between them.

Audi A6 variant Insurance group Estimated premium
A6 40 TDI SE / SE Technik 23-24 around £1,180
A6 40 TFSI S line 34 around £1,470
A6 45 TFSI quattro S line 38 around £1,620
A6 50 TFSI e plug-in hybrid 42 around £1,790
S6 TDI / TFSI 45 around £1,930
RS6 Avant 50 £2,340-plus

Figures are indicative and may change.

Check what your Audi could cost to cover

Compare quotes from 130+ UK insurers in one place

Do S and RS Audi models cost more to insure?

Yes – S and RS Audi models generally cost more to insure than standard versions because they combine higher power output, higher value and higher repair costs. Specialist Audi insurers describe performance models as attracting higher premiums for exactly these reasons, and the A6 range shows the pattern clearly: an RS6 in group 50 can cost roughly double a standard A6 diesel in group 23.

There is no single verified percentage uplift for S or RS cars across all drivers, so treat any “X% more” claim with caution. The group rating does most of the work: an RS3 in a high group will always sit well above an A3 in a low one. Younger drivers with performance Audis often find mainstream insurers reluctant to quote at all, which is where comparing a wider panel helps.

Does Audi offer its own car insurance?

Audi UK offers its own branded car insurance, arranged, underwritten and administered by Liverpool Victoria Insurance Company Limited, part of Allianz, with Essentials and Plus cover levels. Audi does not publish representative premiums, so you need a quote to see the price, and you can usually pay annually or by monthly Direct Debit. Audi-branded cover is designed around the marque, which some owners value, but it is one option rather than automatically the cheapest.

The only reliable way to know whether Audi’s own policy, a specialist Audi insurer, or a mainstream insurer gives you the best value is to compare them on the same car and driver details. Searching whether “audi car insurance” branded cover beats the wider market is exactly what a comparison does in a few minutes. Free Price Compare sources its pricing from a panel of 130+ insurers, so you can place Audi-branded cover alongside the rest.

See how Audi-branded cover compares

Do new alloys or modifications affect Audi insurance?

New alloys and other modifications must be declared to your insurer, because changing wheels, remapping the engine, lowering the suspension or adding body styling counts as a modification that can raise your premium. Failing to disclose a modification can leave a claim reduced or refused, and in serious cases the policy voided. Aftermarket alloys often increase the price slightly because they can raise the car’s value and theft appeal.

Around 98-99% of the cars quoted through Free Price Compare have no modifications, so most Audi owners are unaffected. If you do modify your Audi – a common temptation on S line and performance trims – declare every change and compare again, because insurers price modifications very differently. Factory-fitted options such as larger wheels specified when the car was built are usually part of the standard trim and group rating, not a modification.

How do you reduce the cost of Audi car insurance?

You reduce the cost of Audi car insurance by comparing insurers, building a no-claims bonus, choosing a sensible excess and keeping your mileage and security realistic. Prices for the same Audi vary significantly between insurers, so shopping around is the single most effective step. Our Audi car insurance comparison lets you see a range of quotes side by side.

  • Protect and build your no-claims bonus – each claim-free year earns a larger discount.
  • Pick a voluntary excess you could afford if you claimed, to lower the premium.
  • Keep your estimated annual mileage accurate – under-stating it can invalidate cover, over-stating it costs you.
  • Park off-road or in a garage where possible, and keep factory security and a tracker active on higher-value models.
  • Consider telematics if you are a younger driver, as a telematics policy can reward careful driving.

Paying annually usually costs less than monthly instalments, because monthly premium finance adds interest. The FCA reported in 2026 that motor premium-finance interest rates had fallen by an average of 4.1 percentage points since 2022, saving around £8 a year on a typical policy – but paying in one go still avoids the charge entirely where you can afford it.

Compare car insurance quotes now

Which cover level should Audi owners choose?

Comprehensive cover is the level most Audi owners choose, and it is the top tier, paying for damage to your own Audi as well as to other people, their vehicles and property. Around 88-89% of the car insurance quotes we see are for comprehensive, rising to around 88-91% of actual purchases – a clear signal that for a valuable car it is usually the sensible default.

The two lower levels are third party, fire and theft, which covers you for fire and theft of your car plus damage to others, and third party only, the legal minimum under the Road Traffic Act 1988. Comprehensive is often similarly priced or even cheaper than lower tiers for mainstream drivers, so on an Audi it rarely pays to downgrade. If you are weighing the middle option, our guide to third party fire and theft cover sets out what it does and does not include. For an Audi e-tron or other EV, an electric car insurance policy should also cover the battery and charging equipment.

Which cover level should Audi owners choose

FAQs about audi car insurance

How much does Audi TT car insurance cost?

Audi TT insurance is estimated at around £650-£950 a year for a typical adult driver on 2026 market data, reflecting its sports-coupe styling and mid-to-higher insurance group. A new or young driver will pay considerably more, often several times that figure, because of limited driving experience. The exact price depends on the trim, your age, postcode, mileage and claims history.

How much is Audi A1 insurance for a 17-year-old?

Insuring an Audi A1 as a 17-year-old new driver typically costs far more than the standard-driver estimate of around £450-£650, because teenage drivers are priced as the highest-risk group. Realistic premiums often run well into four figures, though a black box or telematics policy can bring the price down by rewarding safe driving. Comparing a wide panel of insurers is important, as prices for young drivers vary enormously.

Is Audi car insurance more expensive than other makes?

Audi car insurance is not automatically more expensive than other makes – it depends entirely on the model and group. A diesel A1 or A3 in a low insurance group can cost less than many mainstream hatchbacks, while an S or RS model in group 45-50 sits at the top of the market. There is no verified single percentage uplift for Audi over other brands.

Does Audi insurance cover the e-tron battery?

A policy for an Audi e-tron should cover the car including its battery, whether owned or leased, but you must check the wording as some insurers treat leased batteries differently. Specialist and EV-aware insurers typically include charging cables and home charging equipment against damage or theft. Always confirm that battery damage and charging accidents are covered before you buy.

Can I pay for Audi car insurance monthly?

Yes, most Audi insurers and Audi's own branded policy let you pay monthly by Direct Debit instead of annually. Monthly payment usually adds interest through premium finance, so the total cost is higher than paying in one go. The FCA reported falling premium-finance rates in 2026, but paying annually still avoids the charge where you can afford to.

Do new alloy wheels increase my Audi insurance?

Aftermarket alloy wheels count as a modification and should be declared, and they can slightly increase your premium by raising the car's value and theft appeal. Failing to declare them risks a claim being reduced or refused. Larger wheels specified as a factory option when the car was built are usually part of the standard trim rather than a modification.

What is the average UK car insurance premium in 2026?

The average UK private motor insurance premium was £560 in Q1 2026, according to the ABI, which measures what customers actually paid rather than quoted prices. That was £20 lower than Q1 2025 and broadly stable on the previous quarter. A well-chosen small Audi can sit near this average, while larger or performance models cost significantly more.

What does my Audi insurance group number mean?

Your Audi's insurance group is a rating from 1 to 50 set by the Insurance Group Rating Panel using Thatcham Research data, with a higher number meaning higher expected claims costs and usually a higher premium. Audi models span from around group 9 for a small A1 to group 50 for an RS6. The group is the single clearest guide to how much a particular Audi will cost to insure.

Is Audi's own branded insurance cheaper than comparing?

Audi's branded insurance, underwritten by Liverpool Victoria Insurance Company Limited as part of Allianz, is one option rather than automatically the cheapest or most expensive. It does not publish representative prices, so you need a quote to compare. The only reliable way to find the best value is to place it alongside specialist and mainstream insurers using the same car and driver details.

Why won't some insurers add a young named driver to an Audi?

Some insurers decline to add a young named driver, particularly to a higher-group or performance Audi, when the driver has held a licence for less than a year or is seen as high risk. This is a commercial risk decision and varies between insurers. Comparing a wider panel often finds a company willing to quote, and telematics cover can help where mainstream insurers are reluctant.

Does a higher excess lower my Audi premium?

Yes, choosing a higher voluntary excess usually lowers your Audi insurance premium, because you agree to pay more towards any claim yourself. The excess is the amount you contribute before the insurer pays the rest, combining any voluntary amount with the compulsory excess set by the insurer. Only set a voluntary excess you could afford if you needed to claim.

Does Audi insurance cover driving in the EU?

Many comprehensive Audi policies include a period of EU driving at the same cover level as the UK, often up to a set number of days a year, but this is not automatic. Check your policy documents for the exact allowance and any conditions. If you drive abroad regularly, confirm the cover level and duration before travelling or arrange an extension.

Also Read Related Articles


Information correct as of 20 October 2026. Prices, tariffs, policy details and providers change frequently, so please check the latest details before making a decision. This article is for general information only and does not constitute financial advice. Free Price Compare is authorised and regulated by the Financial Conduct Authority (FCA).

4000+ reviews