


Coast Caravan Insurance Explained: Cost & Cover

Written by Pratik Aghera
Reviewed by Andrea Troy
7 min read
Updated: 6 Nov 2026
Coast Caravan Insurance Explained: Cost & Cover

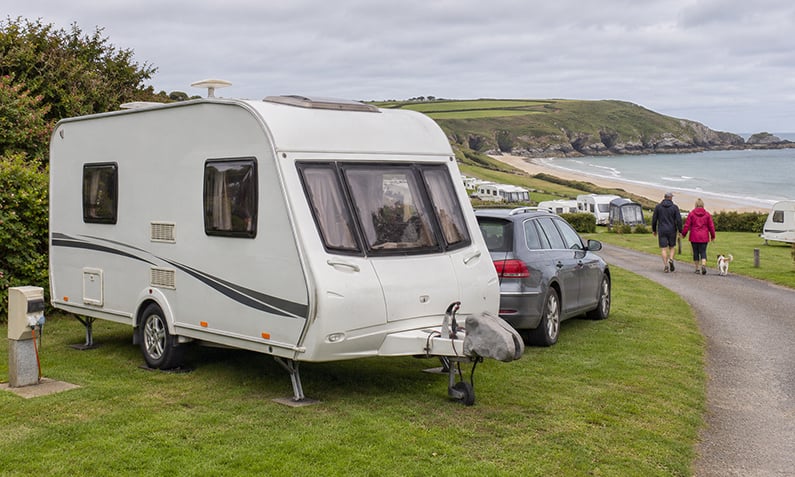
Coast caravan insurance is specialist cover for statics, tourers, folding campers and trailer tents, with Coast advertising prices starting from £73.19 a year for static caravans and from £50 a year for touring caravans. Check the provider’s current price before applying. Coast is a family-run UK insurance broker that arranges policies covering fire, flood, storm, theft, malicious damage, impact and accidental damage, subject to the policy terms.

If you own or are about to buy a caravan, the two questions that matter most are: do you need cover at all, and which type of policy fits how you actually use it. Caravan insurance is not a legal requirement in the UK, but most holiday parks and caravan clubs ask for it, and your own car insurance will not pay for damage to a caravan you are towing. We compare van and specialist insurance from a panel of UK providers, and this explainer sets out what Coast covers, the realistic price range, and how discounts such as a no-claims bonus work.

Quick Answer: Coast Caravan Insurance Explained

  • Caravan insurance is not legally required in the UK, but most parks insist on it.
  • Coast touring cover offers up to 30% no-claims bonus plus a 15% caravan-club discount.
  • Touring and folding-camper policies list up to £2 million public liability.
  • Loss-of-use benefit of £50 per day up to £1,500 is included on tourer policies.
  • Your car insurance covers third-party towing liability, not damage to the caravan itself.

Last updated: October 2026

Written by the Free Price Compare editorial team | Reviewed October 2026

What Coast caravan insurance actually covers

Coast caravan insurance covers accidental and malicious damage, fire, flood, storm, theft and impact across statics, tourers, folding campers and trailer tents, with cover available on either a market-value or new-for-old basis (Coast Insurance, static caravan page updated 3 October 2025). The exact protection depends on the caravan type and the policy level you choose at quotation.

Static caravan policies list additional benefits including loss of rent, legal expenses, site clearance, frozen-food cover and alternative accommodation, all subject to policy terms. Touring caravan and folding-camper policies list a loss-of-use benefit of £50 per day up to £1,500, which helps towards a replacement during repairs, along with European cover for trips abroad.

New-for-old replacement is available on Coast touring caravans up to 15 years old and on folding campers and trailer tents up to 20 years old, provided the sum insured is adequate (Coast Insurance, pages updated March and October 2025). New-for-old means a damaged caravan is replaced with an equivalent new model rather than paid out at its depreciated value, which is the key difference from market-value cover.

Does it cover accidental damage?

Yes, Coast caravan policies include accidental damage as a listed risk alongside fire, flood, storm, theft, malicious damage and impact (Coast Insurance, March and October 2025). Accidental damage means unintended physical harm to the caravan, such as a stone strike, a reversing knock or a dropped awning pole, as distinct from gradual wear and tear, which most policies exclude.

Cover limits, excesses and any security conditions apply, so check whether an alarm, hitch lock or wheel clamp is required for theft claims to be valid. If you want to understand how specialist cover compares across providers, our caravan insurance cost and cover guide breaks down the standard protections in plain English.

Compare caravan cover options

How much does Coast caravan insurance cost?

Coast caravan insurance is advertised from £73.19 a year for static caravans and from £50 a year for touring caravans on Coast Insurance’s product pages. Check the provider’s current price before applying. These are starting prices for the lowest-risk profiles, so your own quote will depend on the caravan’s value, where it is kept, its age and the security you have fitted.

Static caravan insurance prices vary widely according to the caravan’s value, location, use and security. A modest inland caravan will generally cost less to insure than a high-value coastal lodge.

Static caravan insurance cost is driven mainly by replacement value, park location and whether the van is sub-let or used residentially. Coastal sites can attract higher premiums because of storm and flood exposure, while strong security and a quiet inland pitch can reduce the price.

Caravan type Coast advertised from Typical cover basis
Static caravan £73.19 a year Market value or new-for-old
Touring caravan £50 a year New-for-old up to 15 years old
Folding camper / trailer tent Quote-based New-for-old up to 20 years old

Figures are indicative and may change.

Is caravan insurance expensive?

Caravan insurance can be relatively inexpensive compared with the value it protects, with Coast advertising touring cover from £50 a year and static cover from £73.19 a year. Check the provider’s current price before applying. Whether it feels expensive depends on the value you are protecting: insuring a £60,000 lodge naturally costs more than insuring a modest second-hand tourer.

The headline premium is not the only cost to weigh. Check the excess you would pay on a claim, any security conditions, and whether the sum insured is high enough to trigger a full new-for-old replacement, because underinsurance can reduce a payout.

How much does Coast caravan insurance cost

Protecting a tourer or static?

See how specialist caravan cover compares before you renew.

Caravan insurance is not a legal requirement in the UK, and Coast confirms there is no law forcing you to insure a static or touring caravan (Coast Insurance, page updated 1 March 2025). The legal position differs from car insurance, which is compulsory under the Road Traffic Act 1988.

In practice, most UK holiday parks and caravan clubs make insurance a condition of keeping a van on their site, and many lenders require it if the caravan is financed. For tourers, the real exposure is theft and accidental damage on the road and on site, neither of which your car policy pays for.

If you are buying a static on a park, read the site licence terms before you sign, because the park sets its own insurance conditions. A common misconception is that the park’s own cover protects your van; it rarely does beyond the park’s buildings and public areas.

Is static caravan insurance mandatory?

Static caravan insurance is not mandatory by law, but almost all holiday parks make it a contractual condition of your pitch agreement. Parks do this because an uninsured static that is damaged in a storm or fire can leave the owner unable to repair or remove it, which affects the whole site.

Owners often report park insurance requirements in the region of a few hundred pounds a year once site fees, rates and insurance are combined, so budget for the full running cost, not just the premium. Shopping the cover separately rather than taking the park’s recommended policy can reduce what you pay.

See typical caravan insurance prices

Does my car insurance cover my caravan while towing?

Your car insurance covers your third-party liability while towing a caravan, but it does not cover accidental or storm damage to the caravan itself. In practice, if you jackknife and damage another vehicle, your car policy responds to that third-party claim, but the repair bill for your own caravan falls to a separate caravan policy.

This split catches many owners out. The towing vehicle’s insurer deals with injury or damage you cause to others; the caravan’s own insurance deals with damage the caravan sustains, including theft, impact and malicious damage while hitched or parked. Check your car policy wording for any towing conditions, as some restrict cover to third-party only while a trailer is attached.

Am I insured to tow someone else’s caravan?

You are generally only insured to tow someone else’s caravan if your own car insurance allows towing and the caravan has its own insurance for damage it sustains. Towing a friend’s caravan on your policy means your insurer covers third-party liability for the towing, but the caravan’s own policy should cover damage to the caravan while in transit.

Before agreeing to tow, confirm three things: your licence category permits the combined weight, your car insurance does not exclude towing a trailer, and the caravan itself is insured. Driving licence towing entitlements changed in late 2021, so most drivers who passed after 1997 can now tow larger trailers, but checking your entitlement on gov.uk avoids an invalid claim.

What discounts can lower your Coast touring caravan insurance?

Coast touring caravan insurance lists a no-claims bonus of up to 30%, a 5% discount for an alarm or Datatag, and a 15% caravan-club membership discount (Coast Insurance, page updated 1 March 2025). These are stated policy discounts rather than guaranteed savings, and they stack subject to the policy terms.

A no-claims bonus is a discount insurers apply for each consecutive year you do not make a claim, in the same way it works on car insurance. On a touring caravan, protecting that bonus and avoiding small claims can matter more over time than chasing the lowest headline premium.

  • Fit and declare an alarm or a Datatag security marking to qualify for the 5% security discount.
  • Join a recognised caravan club to access the 15% membership discount.
  • Build and protect your no-claims bonus towards the maximum 30%.
  • Keep the sum insured accurate so a new-for-old claim is not reduced for underinsurance.

For tourers specifically, our tourer caravan insurance guide explains how cover levels and security conditions affect the price. If you also run a van for work, compare that cover through our van insurance comparison so your class of use is correctly set.

Compare tourer caravan cover

Should you buy a static caravan on a coastal holiday park?

Buying a static caravan on a coastal holiday park can be worthwhile for regular holidays, but the running costs extend well beyond the purchase price. Owners typically face annual site fees, local rates where applicable, utilities and insurance, which together often run to several thousand pounds a year before any travel or maintenance.

Coastal pitches can carry higher insurance premiums than inland parks because of storm and flood exposure, and site licences usually restrict the van to holiday use rather than a permanent residence. Before buying, confirm the pitch licence length, the park’s insurance requirement, whether sub-letting is allowed, and how depreciation affects resale, because statics rarely hold value like property.

Read the site agreement carefully for annual fee increases and the park’s rules on removal or resale, as these terms vary widely between parks. Treating a static as a holiday asset rather than an investment, and insuring it correctly, avoids the most common regrets owners report.

Caravan insurance arrangers such as Coast are regulated by the Financial Conduct Authority (FCA), and eligible policies fall under the Financial Services Compensation Scheme, with complaints routed through the Financial Ombudsman Service if a dispute cannot be resolved.

Should you buy a static caravan on a coastal holiday park

FAQs about coast caravan insurance

How much is Coast caravan insurance?

Coast advertises static caravan insurance from £73.19 a year and touring caravan insurance from £50 a year, based on its 2025 product pages. These are starting prices for lower-risk profiles, so your actual quote depends on the caravan’s value, age, location and security. Coastal and high-value lodges tend to cost more than modest inland tourers.

Does Coast caravan insurance cover European trips?

Coast lists European cover on touring caravan and folding-camper policies, allowing you to take the caravan abroad within the policy limits. The permitted duration and territorial conditions vary by policy, so confirm the exact wording at quotation. Always check whether your towing vehicle’s insurance also extends to Europe for the same trip.

What does static caravan insurance cover?

Static caravan insurance covers risks such as fire, flood, storm, theft, malicious damage, impact and accidental damage to the caravan and its contents. Coast policies also list benefits like loss of rent, legal expenses, site clearance, frozen-food cover and alternative accommodation, subject to the policy terms. Cover can be arranged on a market-value or new-for-old basis.

Can I get new-for-old cover on an older caravan?

Coast offers new-for-old replacement on touring caravans up to 15 years old and on folding campers and trailer tents up to 20 years old, provided the sum insured is adequate. Beyond those ages, cover is usually arranged on a market-value basis, which pays the depreciated value rather than the cost of a new replacement. Keeping the sum insured accurate is essential for a full new-for-old payout.

Do holiday parks require caravan insurance?

Most UK holiday parks make caravan insurance a condition of your pitch agreement, even though it is not a legal requirement. The park sets its own minimum requirements, which often include public liability cover. You are usually free to arrange the cover yourself rather than taking the park’s recommended policy, which can reduce what you pay.

What happens if I tow without the right insurance?

If you tow without valid car insurance that permits towing, any third-party claim could be rejected and you may be driving illegally. Separately, if the caravan has no insurance of its own, damage it sustains while towed or parked is not covered. Always confirm both your car policy and the caravan’s own policy before setting off.

Does caravan insurance cover theft on a site?

Coast caravan policies list theft as a covered risk, but payouts usually depend on meeting any security conditions in the policy. Fitting and using an alarm, hitch lock, wheel clamp or a Datatag marking can be required for a theft claim to be valid. Check the specific security requirements in your policy schedule.

Can I insure a caravan I live in permanently?

Residential or permanently sited use is treated differently from holiday use and often costs more, because the risk profile changes. Coast states a reduced-rate policy is available for permanently sited touring caravans, but you must declare the true use at quotation. Failing to disclose residential use could invalidate a claim under the Consumer Insurance (Disclosure and Representations) Act 2012.

Is static caravan insurance worth it?

Static caravan insurance is usually worth it because the cost of repairing or replacing a damaged static after a storm, fire or theft far exceeds the annual premium. Most parks also make it a condition of keeping the van on site. Weigh the premium against the caravan’s replacement value and your park’s requirements.

How can I reduce my caravan insurance premium?

You can reduce your caravan insurance premium by building a no-claims bonus, fitting approved security such as an alarm or Datatag, joining a recognised caravan club for a membership discount, and choosing a secure, lower-risk storage location. Keeping the sum insured accurate avoids both overpaying and underinsurance. Comparing specialist providers before renewing is the quickest way to check you are paying a fair price.

Does caravan insurance cover accidental damage while parked?

Yes, Coast caravan policies list accidental damage as a covered risk, which can include unintended damage while the caravan is parked or on site. This covers events such as impact or a knock during manoeuvring, subject to the excess and policy conditions. Gradual wear, deterioration and poor maintenance are normally excluded.

Is my park home covered by caravan insurance?

Park homes are a distinct category and are usually insured under a dedicated park home policy rather than standard caravan insurance. Coast arranges park home cover separately because the risks and construction differ from holiday statics and tourers. If your home is residential and on a protected site, ask specifically for park home cover at quotation.

Also Read Related Articles


Information correct as of 19 October 2026. Prices, tariffs, policy details and providers change frequently, so please check the latest details before making a decision. This article is for general information only and does not constitute financial advice. Free Price Compare is authorised and regulated by the Financial Conduct Authority (FCA).

4000+ reviews