


Temp Car Insurance: What It Costs and How It Works

Written by Pratik Aghera
Reviewed by Andrea Troy
6 min read
Updated: 18 Sep 2026
Temp Car Insurance: What It Costs and How It Works

Temp car insurance is short-term cover that insures you to drive a specific car for a set period, from as little as one hour up to around 28 days, without taking out a full annual policy. It works as a standalone policy in your name, so making a claim does not affect the car owner’s no-claims bonus.

Prices sit at the low end for hourly and daily cover: RAC says one-day cover costs £23.99, while its Demand Index shows the average price for one day of temporary cover was £23.99 between 1 January and 30 June 2026. Cover is nearly always comprehensive, activates almost immediately once you buy, and is popular for borrowing a car, test drives, driving a newly bought vehicle home, or sharing driving on a long trip.

This explainer sets out what temporary cover is, what it typically costs by duration, when it beats an annual policy, and the practical checks to make before you buy.

Quick Answer: Temp Car Insurance

  • Temp car insurance runs from around 1 hour to 28 days and is a standalone policy, so a claim does not touch the car owner’s no-claims bonus.
  • A single day averaged £23.99 across January to June 2026, while a full week averaged around £8.14 per day (RAC Demand Index).
  • Per-day cost falls sharply as the term lengthens, so a week is usually far cheaper per day than buying seven separate one-day policies.
  • Almost all temporary policies are fully comprehensive, and the car must already have a valid MOT and be roadworthy for cover to apply.
  • You cannot tax a car using temporary insurance because it is not always logged on the Motor Insurance Database in the way the DVLA tax check requires.

Last updated: September 2026

Written by the Free Price Compare editorial team | Reviewed September 2026

What is temp car insurance and how does it work?

Temp car insurance is a standalone motor policy that covers one named driver to use a specific vehicle for a short, fixed period, usually from one hour to 28 days. The cover sits entirely in the driver’s name, separate from any existing annual policy on the car, which is why it is used when you borrow, test drive, or briefly need a vehicle that is not your own. Because it is a fresh policy rather than an add-on, a claim made on temporary cover does not affect the car owner’s no-claims bonus. Cover is almost always fully comprehensive, and it typically activates within minutes of purchase, with your details added to the Motor Insurance Database so police ANPR cameras can confirm the car is insured.

Free Price Compare compares car insurance from a panel of 130 or more insurers, and short-term policies work on the same legal footing as annual ones: you must meet the minimum third-party requirement of the Road Traffic Act 1988 to drive on a public road. For a fuller breakdown of durations, our guide to short car insurance from 1 hour to 28 days walks through each length in turn.

How much does temporary car insurance cost?

A single day of temporary car insurance averaged £23.99 between 1 January and 30 June 2026, according to the RAC Demand Index. Costs rise with the number of hours or days you buy, but the per-day rate drops steeply the longer the term. The RAC Demand Index says weekly cover works out at around £8.14 per day, based on a £56.99 weekly price. Your exact price still depends on your age, driving history, the car’s value and where you live, so treat these as typical figures rather than a fixed quote.

Duration Typical price Roughly per day
1 hour around £16
1 day around £24 around £24
3 days around £39 around £13
1 week around £57 around £8
4 weeks around £109 around £4

Figures are indicative and may change. They are drawn from published RAC example pricing for early to mid 2026 and vary by driver profile.

The wider motor market is settled at the moment, which helps keep short-term pricing stable. The average comprehensive annual premium was £560 in Q1 2026, according to the ABI Motor Insurance Premium Tracker, a £1 rise on the previous quarter and £20 lower than a year earlier.

See what short-term cover would cost you

Is temporary car insurance expensive compared with an annual policy?

Temporary car insurance is not automatically more expensive than annual cover, and for short spells it is usually cheaper overall than buying a whole year. Buying a week of cover for around £57 costs far less in total than a full annual policy, even though the per-day rate looks high. The trap is duration: because per-day pricing falls the longer you buy, stringing together repeated short policies for a car you use most weeks becomes poor value fast. A useful rule of thumb is that if you will need a car for more than about six to eight weeks in total across a year, an annual policy or being added as a named driver is often cheaper.

For a car you only drive occasionally, short-term cover avoids paying twelve months for a few days of use. If you are unsure whether to insure a borrowed car this way or join the owner’s policy, our guide on driving someone else’s car compares both routes.

Can I get temp cover on a car that’s already insured?

Yes, you can take out temp car insurance on a vehicle that already has an annual policy, and this is one of the most common uses. Your short-term policy runs alongside the owner’s annual cover as a separate contract in your name, so any claim you make sits on your record, not theirs, leaving their no-claims bonus untouched. This matters if you are borrowing a friend’s or family member’s car, because it protects the owner from a premium rise if something goes wrong while you are driving. The owner does not need to cancel or alter their existing policy for your temporary cover to be valid.

One caution: some higher-value or heavily modified cars fall outside short-term underwriters’ criteria, so a small number of vehicles cannot be covered this way. Around 98 to 99 percent of cars quoted through Free Price Compare have no modifications (Free Price Compare data, January to June 2026), which is why most standard cars qualify without issue.

Can I get temp cover on a car that’s already insured

Need cover for a day or a week?

Compare short-term car insurance options across a panel of UK insurers.

Does making a claim affect the car owner’s No Claims Discount?

No, a claim on temp car insurance does not affect the car owner’s no-claims discount, because the temporary policy is a separate contract in the driver’s name. If you borrow a car and have an accident while covered by your own short-term policy, the claim is recorded against you, and the owner’s annual policy and no-claims bonus are not involved. This is the single biggest advantage of temporary cover over being added as a named driver, where an at-fault claim can reduce or wipe out the main policyholder’s accumulated discount. The owner keeps their protected years intact.

Bear in mind your own future short-term or annual quotes may be affected by a claim on your temporary policy, since it becomes part of your claims history. Insurers can see prior claims through shared industry databases regardless of policy length.

Can I drive a car I’ve just bought without insurance?

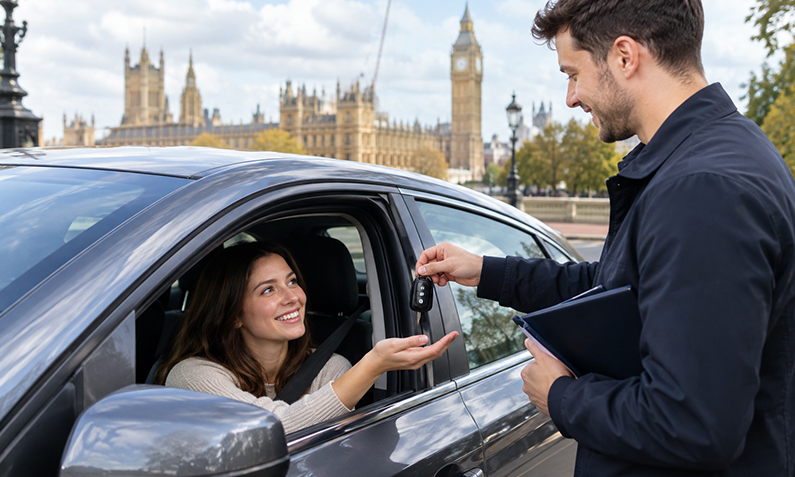
No, you cannot legally drive a car you have just bought without insurance, even for the journey home, because the Road Traffic Act 1988 requires valid cover before any vehicle is used on a public road. Driving away uninsured risks a fixed penalty, points, and the car being seized. Temporary car insurance solves this neatly: a one-day or few-hour policy in your name lets you drive a newly purchased car home the moment you buy it, before you arrange annual cover. You will need the vehicle registration and, for many insurers, confirmation you are the new keeper.

Short-term cover activates almost immediately, which is why so many buyers arrange it on their phone at the point of sale. Our short guide to 1 day car insurance explains exactly how single-day cover works for collecting a car.

Sort cover before you drive it home

Can I tax my car with temporary insurance?

No, you generally cannot tax a car using temporary insurance, because the DVLA tax check relies on the vehicle showing as continuously insured on the Motor Insurance Database, and short-term policies are not always recorded there in the format the tax system requires. To tax a car through the DVLA you normally need an annual policy in force. If you have bought a car and need both tax and cover to drive it away, arrange an annual policy that logs on the database, then tax the vehicle online.

Continuous Insurance Enforcement rules mean a car kept on the road must be insured at all times, and a Statutory Off Road Notification is required if it is kept off-road untaxed and uninsured. Temporary cover suits driving, not the paperwork chain of taxing a vehicle for ongoing use.

Are car insurance quotes more expensive at the weekend?

Weekend temporary car insurance quotes are not systematically more expensive purely because it is a Saturday or Sunday, but demand-based pricing means popular short durations can cost more when more people are buying. Short-term underwriters price continuously on risk and demand, so a busy weekend day or a bank holiday can see slightly higher rates than a quiet weekday for the same cover. Most temporary insurers operate online around the clock, so you can buy at any time, including weekends and evenings, without waiting for office hours.

If price flexibility matters, checking a quote midweek and comparing it to a weekend quote for the same dates can reveal any difference. Since roughly 8 in 10 Free Price Compare car insurance journeys happen on a mobile device (Free Price Compare data, January to June 2026), buying short-term cover on a phone the moment you need it is the norm.

Who is temporary cover a good fit for?

Temporary cover suits drivers who need a car for a short, defined spell rather than year-round, and it is most cost-effective for occasional use. Common situations where it works well include borrowing a relative’s car, sharing the driving on a long trip, collecting a newly bought vehicle, insuring a spare car for a visitor, or covering a learner practising in a family car. Learner drivers can use dedicated short-term learner cover, explained in our learner car insurance guide, which protects the supervising driver’s own policy during practice.

  • Borrowing a friend’s or family member’s car for a weekend or a single trip.
  • Driving a car you have just bought home before arranging annual cover.
  • Adding an extra driver to share a long journey without altering the annual policy.
  • Insuring a second or spare car used only now and then.

If you also run a van, similar rules apply, and our guide to temporary van insurance covers the equivalent short-term options for light commercial vehicles.

Compare car insurance across 130+ insurers

How to get cheap temp car insurance

The cheapest temp car insurance comes from matching the exact duration you need and buying the right car for the risk, rather than defaulting to the shortest slice. Because per-day cost drops sharply with length, buying a week when you need six days is often barely more than five separate daily policies and saves the daily admin. Insuring a lower-value, standard car keeps the price down: around 43 to 48 percent of Free Price Compare car insurance quotes are for cars valued between £1,000 and £5,000 (Free Price Compare data, January to June 2026), and these tend to attract lower short-term premiums than high-value models.

  • Buy the full block you need in one policy rather than repeated single days.
  • Give accurate mileage and usage details, since over-stating either can push the price up.
  • Choose a standard, unmodified car where you have the option, as modifications can rule out cover entirely.
  • Compare quotes for the same dates before you buy, as short-term pricing varies between underwriters.

If you are weighing short-term against a cheap annual policy, note that a new driver with no no-claims history can sometimes find a monthly annual policy competitive against several weeks of temporary cover, so it is worth comparing both. Drivers keen to avoid telematics can also read our guide on cheap insurance without a black box.

How to get cheap temp car insurance

FAQs about temp car insurance

What is temporary car insurance?

Temporary car insurance is short-term motor cover that insures one driver to use a specific car for a set period, usually from one hour up to 28 days. It is a standalone policy in the driver's name, activates almost immediately, and is nearly always fully comprehensive. It is commonly used for borrowing, test drives or driving a newly bought car home.

What is the difference between temp cover insurance and an annual policy?

Temp cover insurance runs for a short fixed period and is bought as a fresh standalone policy each time, while an annual policy covers you for twelve continuous months. Temporary cover avoids paying for a full year when you only need a car occasionally, but for regular use across the year an annual policy usually works out cheaper overall.

How much does 1 day car insurance cost in 2026?

A single day of temporary car insurance averaged £23.99 between January and June 2026 according to RAC figures, though individual prices range widely by driver. Younger and higher-risk drivers pay more, while an experienced driver with a clean licence and a modest car typically pays less. Always compare quotes for your exact dates before buying.

Is hourly car insurance available in the UK?

Yes, many short-term insurers offer hourly car insurance, with cover starting from as little as one hour. Published examples put an hour at around £16, though this varies by driver and car. Hourly cover suits a very short journey, such as moving a car a short distance or a brief errand in a borrowed vehicle.

Can I get temporary car insurance on any car?

Temporary car insurance is available for most standard cars, but not every vehicle qualifies. Very high-value cars, heavily modified vehicles and some imports can fall outside short-term underwriters' criteria and may be refused. Standard, unmodified cars are almost always accepted, which covers the large majority of vehicles on UK roads.

Does temporary car insurance cover me third party or comprehensive?

Almost all temporary car insurance policies are fully comprehensive, meaning you are covered for damage to the car you are driving as well as third-party liability. Comprehensive cover also usually includes fire and theft. Always check the policy documents, as excess levels and any exclusions vary between short-term insurers.

Can I get temporary car insurance with a foreign licence?

Some short-term insurers accept EU and certain other foreign driving licences for temporary cover, but acceptance is not universal and depends on the insurer's criteria. If you hold a non-UK licence, check eligibility before you buy, as some products only cover UK licence holders. Rental cars usually include their own cover, so temporary policies mainly apply to borrowed vehicles.

What happens if I need cover for longer than 28 days?

If you need cover for longer than around 28 days, a monthly rolling arrangement or a standard annual policy is usually the better option. While some providers offer longer short-term terms, repeatedly renewing short policies for months on end is rarely good value. Compare the cost of continuous cover against extended short-term cover before deciding.

Will temporary cover show up on the Motor Insurance Database?

Yes, valid temporary car insurance is recorded on the Motor Insurance Database once your policy starts, so police ANPR cameras can confirm the car is insured. There can be a short delay between buying and the record appearing, so keep your policy confirmation to hand when you first drive. Never drive before your cover start time.

Is it cheaper to buy several one-day policies or one longer policy?

Buying one longer policy is almost always cheaper than several separate one-day policies for the same days, because the per-day cost falls sharply as the term lengthens. Weekly cover can work out at roughly a third of the daily rate per day. If you know you will drive on multiple days, buy the whole block in a single policy.

Can a learner driver use temporary car insurance?

Yes, dedicated short-term learner insurance lets a provisional licence holder practise in a family or friend's car without affecting the owner's policy. It runs as a standalone policy, so a claim during practice sits on the learner's record rather than the car owner's no-claims bonus. Cover applies while you hold a provisional licence and are properly supervised.

Can I take out temporary insurance instantly online?

Yes, most temporary car insurance can be bought online in minutes and starts almost immediately, including at weekends and evenings. You typically need the vehicle registration and your licence details. Because cover can begin within minutes, it is well suited to buying at the point you collect a car or before a spontaneous trip.

Also Read Related Articles


Information correct as of 14 September 2026. Prices, tariffs, policy details and providers change frequently, so please check the latest details before making a decision. This article is for general information only and does not constitute financial advice. Free Price Compare is authorised and regulated by the Financial Conduct Authority (FCA).

4000+ reviews